

 Facebook
 X
 Pinterest
 Copy Link
Renovate or Relocate? What To Know Before You Decide To Age in Place
You’ve spent years making your house feel like home, celebrating milestones, making each room your own, and turning neighbors into friends. As you look ahead to the next chapter of your life, it’s natural to wonder if this is still the place you want to spend it.
Whether you’re leaning toward staying in your house as you get older or moving to a 55+ community, the goal is the same: a home that fits the life you want, with more time for the people and things you love. So, here’s what to consider before you decide.
What It Can Take To Stay Put
Wanting to stay in a house you love and are familiar with makes sense. But most houses need at least some updates to make aging in place easier.
In fact, the Joint Center for Housing Studies of Harvard University (JCHS) finds that fewer than 4% of homes have the basics, like single-floor living, no-step entries, and wide hallways and doorways (see graph below):
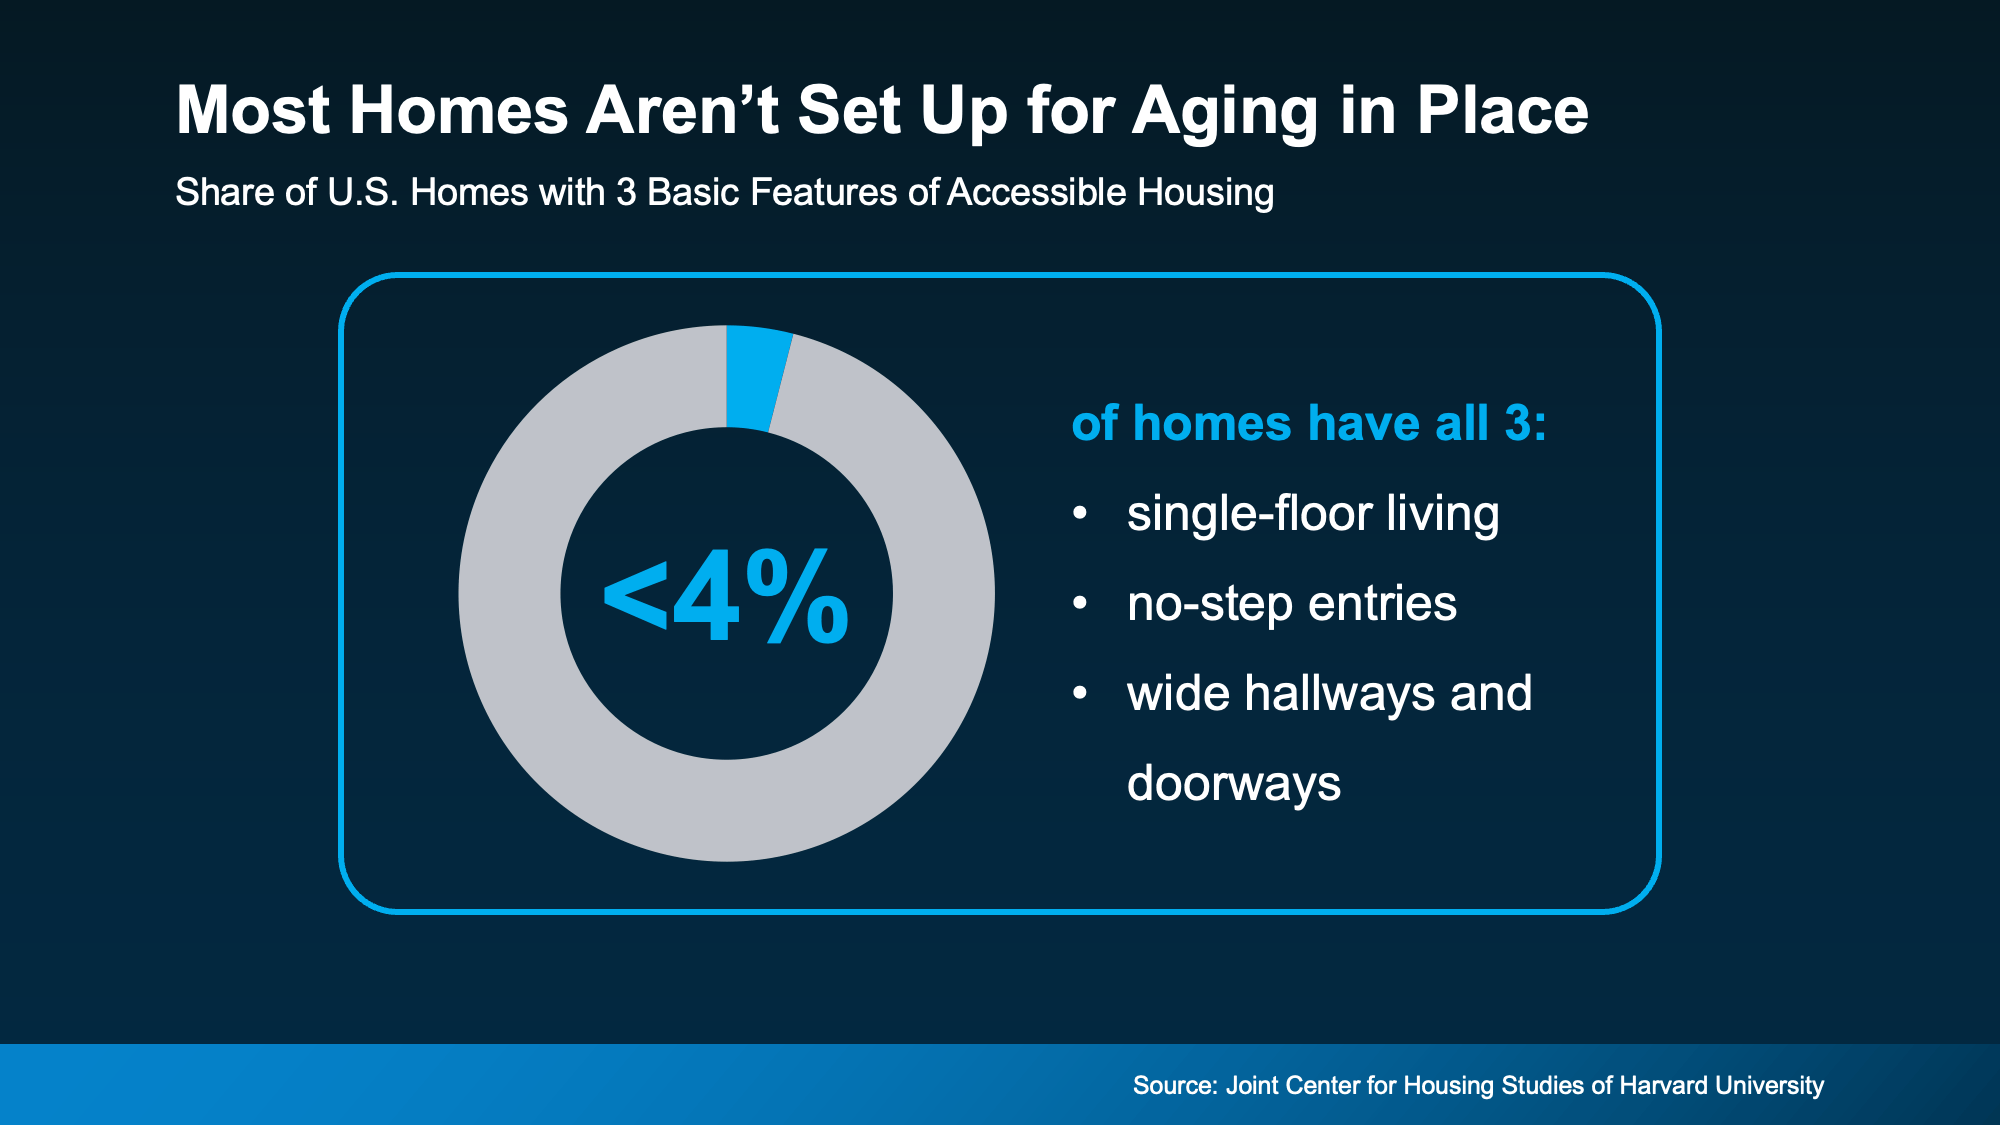
That means for most homeowners, staying put means doing a remodel.
The National Association of Home Builders (NAHB) reports more than half of remodelers (56%) take on this kind of work. Some of the most common projects are installing grab bars, curb-less showers (walk-in showers with no ledge to step over), and wider doorways.
Now, that’s not to say you can’t go this route. You most certainly can. But if this is how you’re leaning just know you’d be living with contractor noise and dust until the work gets done. Some people don’t want to live in a construction zone. Not to mention, having to manage the contractors and schedules, etc.
Your Equity Could Pay for Your Next Move
If that sounds like something you’d rather avoid, here’s the good news. The money for your next home may already be sitting in your current one. It’s called equity, which is the difference between what your house is worth and what you still owe on it. After years of mortgage payments and rising home values, it adds up. Jess Catorc, Co-Founder of Carry, explains:
“The way home equity builds and is used changes a lot depending on your stage of life. . . . For older homeowners, decades of mortgage payments and home-value growth can turn equity into a financial cushion.“
When you sell, that cushion can go toward a home that’s ready for this stage of life. No demo required. You just get the keys and it’s all there, ready for you. That means less time on projects and more time for living. And one option you may consider if you’re entertaining a move is a 55+ plus community.
Why 55+ Communities Are Worth a Look
From the homes to the shared spaces to the activity calendar, these communities are planned around this stage of life. And that means everything you need is already rolled into one place. Rocket Mortgage lists some of the biggest perks (see visual below):
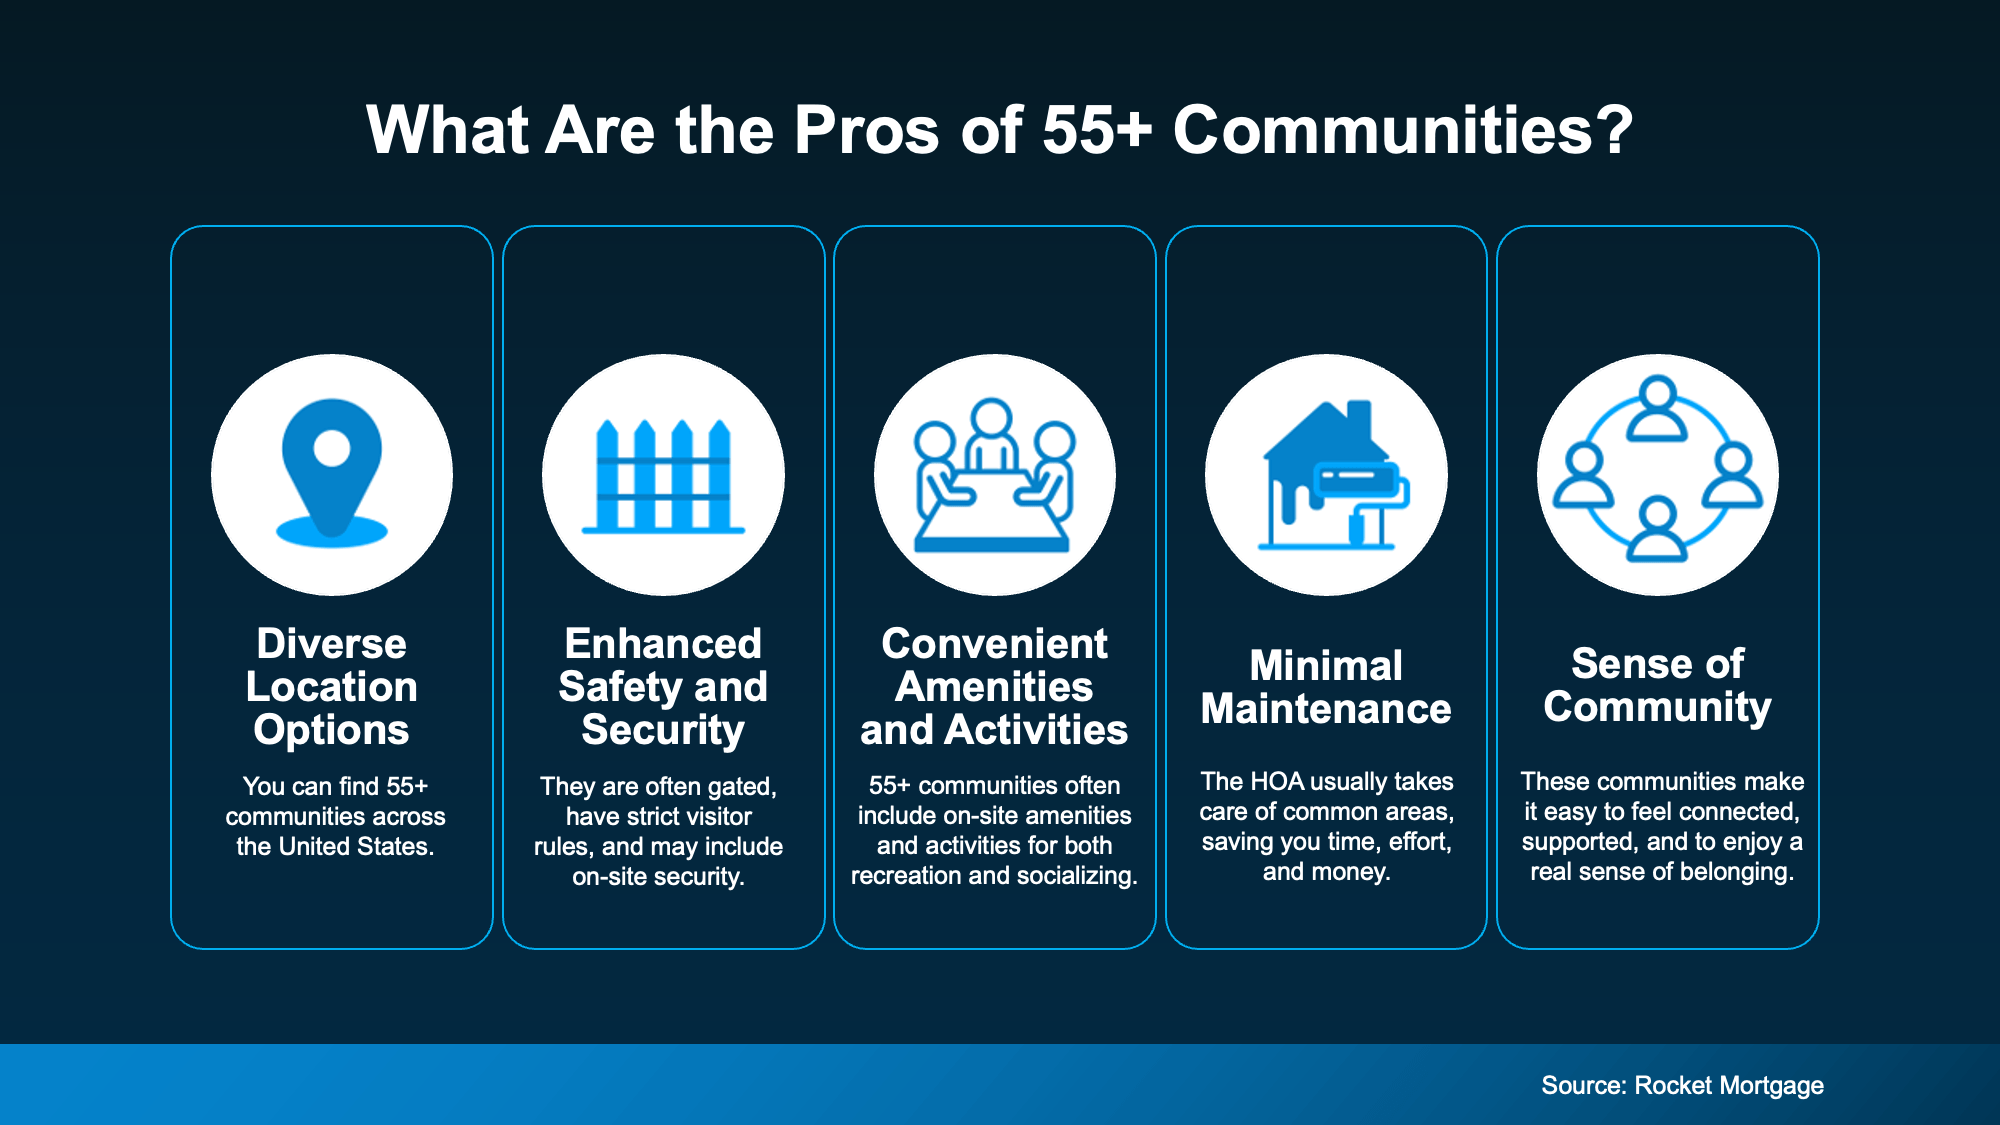
Instead of spending time and money to make your house easier to live in, you’d move into a community that’s designed with that in mind from the jump. That frees you up for the good stuff, like a morning walk with a neighbor, a game night down the street, or finally trying the hobby you’ve been putting off.
Bottom Line
Staying and moving can both be good choices. What matters most is finding the place where you’ll feel comfortable and at home for years to come.
If you’d like help weighing the two, let’s connect. We can look at what your house could sell for and what 55+ communities in our area have to offer, so you can decide what feels right for you.
The Housing Market Split in 2. Which Side Is Your House On?
Knowing which track your house is on changes everything about your sale, from your asking price to how long you can expect to wait before an offer comes in. Here’s what you need to know.
Home Sales Are Picking Up Speed at the Top of the Market
Rates and buyer competition are shaping this market differently depending on price point. Look at recent sales data from the National Association of Realtors (NAR) and the pattern jumps right out.
Homes priced under $250,000 saw sales drop 2-3% compared to last year, while homes priced above $750,000 saw sales climb by double digits (see graph below):
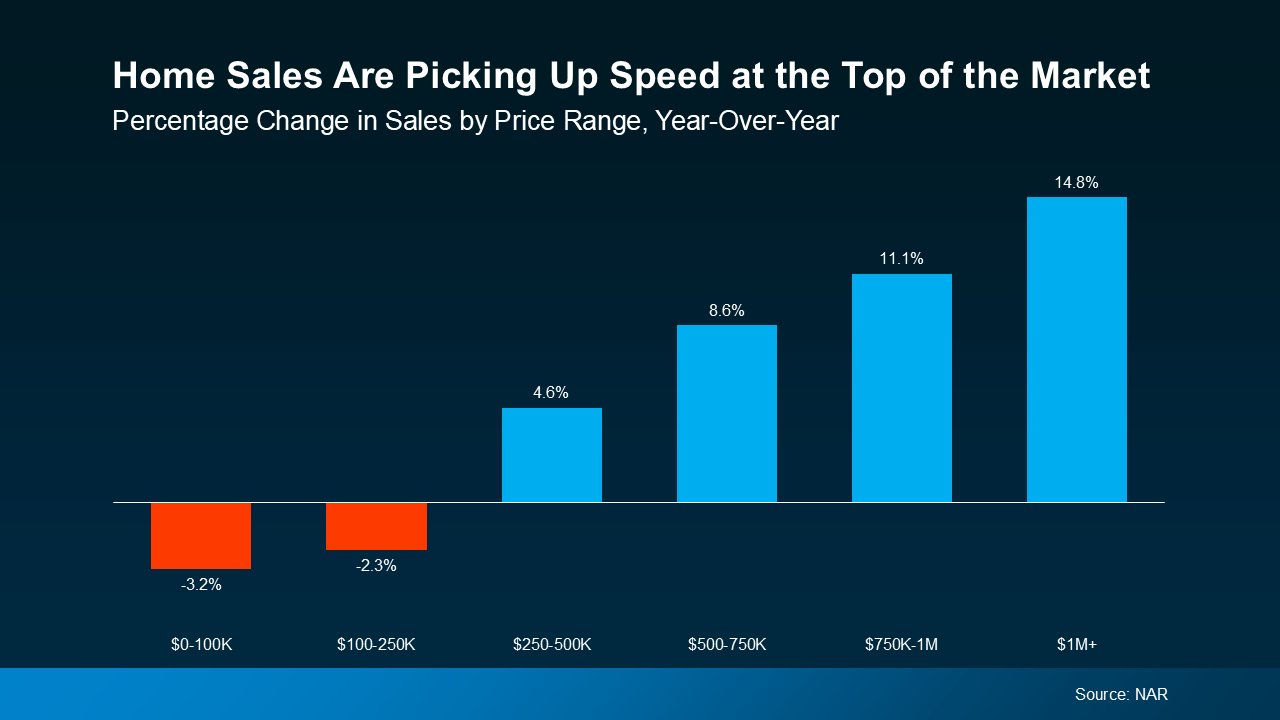 What’s behind the divide? Due to higher rates and the last few years of home price appreciation, fewer buyers can comfortably afford homes at the entry-level price point right now – especially first-time buyers. So, demand in that segment has slowed down.
On the flip side, buyers looking for higher-priced homes have less sensitivity to high-rate environments and more room in their budgets, thanks in part to a strong stock market and their equity in their current home.
That’s the real differentiator. Lower-priced homes are still selling, just not as quickly since today’s rates have shrunk the pool of buyers who can afford to buy their first place right now.
This is exactly why pricing strategy and presentation carry more weight than they used to, especially if you’re selling in that range. Price it right from the start instead of testing a high number, make sure it shows well online and in person, and lean on an agent who can get your listing in front of every buyer shopping in your range. That’s the best way to make sure you catch the attention of one of the buyers who are still looking – and it’s how you prove your home is worth it’s price.
Why Some Homes Sit While Others Get Snapped Up
How fast a home sells is shifting by price point too, and the split is just as sharp. For years, luxury homes sat on the market a lot longer than starter homes. That gap has nearly closed, according to Redfin (see chart below):
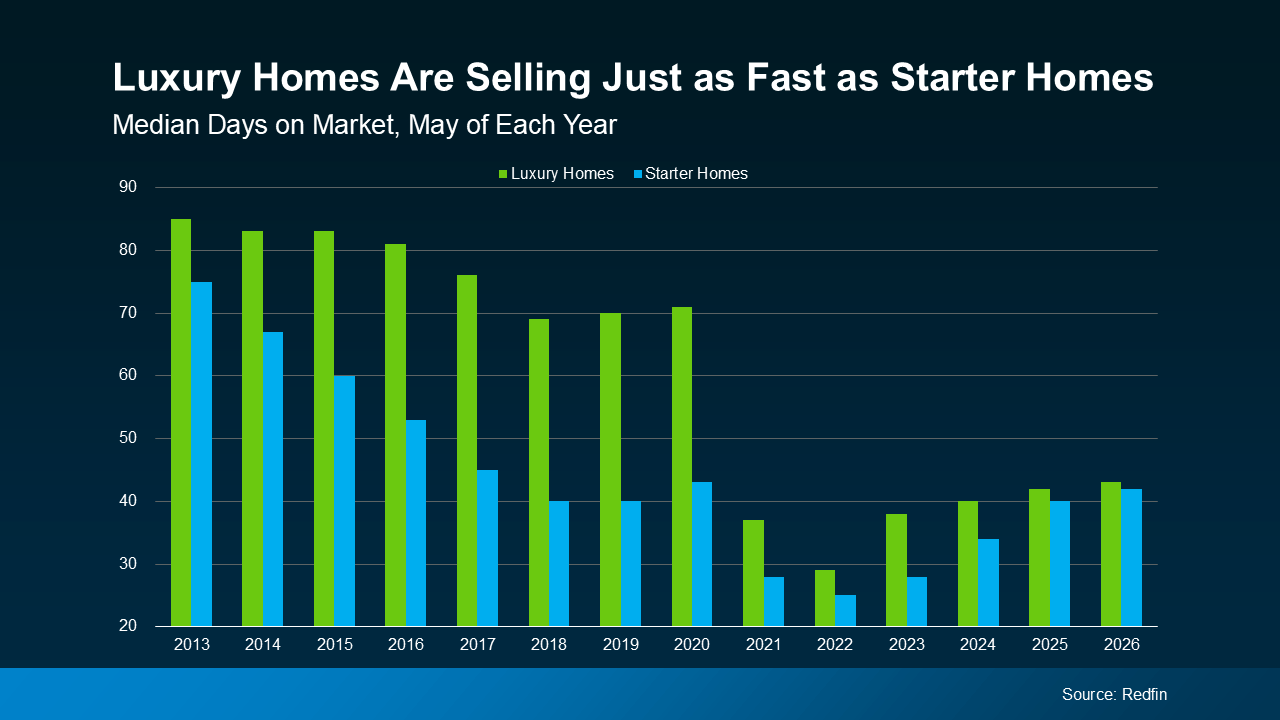 Buyers with deep pockets are moving fast when a well-priced home in their range comes up. As Zillow puts it:
“The U.S. housing market is splitting in two. Luxury homes are selling at a faster pace than a year ago, with shrinking supply and growing bidding wars.”
If you’re in that range, your house may sell faster than you’d expect. You may even get multiple offers. That kind of competition changes how a listing should be marketed and priced from day 1.
And no matter which side you’re on, that’s information you’re going to want up front if you want to have the smoothest sale possible.
What This Means for Your Sale
If you’re thinking about selling an entry-level home, don’t panic. Homes at your price point are still selling, just at a slower pace than last year. That slower pace means pricing and presentation matter even more right now.
If you’re selling a move-up or luxury house, you’re in a good spot right now. Buyers looking in your price point usually aren’t as affected by today’s rates, so they’re more active, and good listings are drawing real competition.
Either way, your price point is the biggest factor in how fast your house sells and what it sells for.
Bottom Line
Your home’s price point is the real story right now, more than anything you’re hearing in national headlines. Let’s map out exactly where your house fits in this split market and build a pricing strategy that gets you the speed and price you’re after. Give me a call today, Liz Norvelle (928) 458-4025.
Thinking About Waiting for Lower Mortgage Rates? Read This First.

A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today’s forecasts, that may not happen. And you should know that before you decide what to do.
Let’s look at why experts don’t expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.
1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way
If you’re waiting for rates to fall, you’re not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.
The challenge is, that’s not what the experts who study mortgage rates every day are expecting.
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):
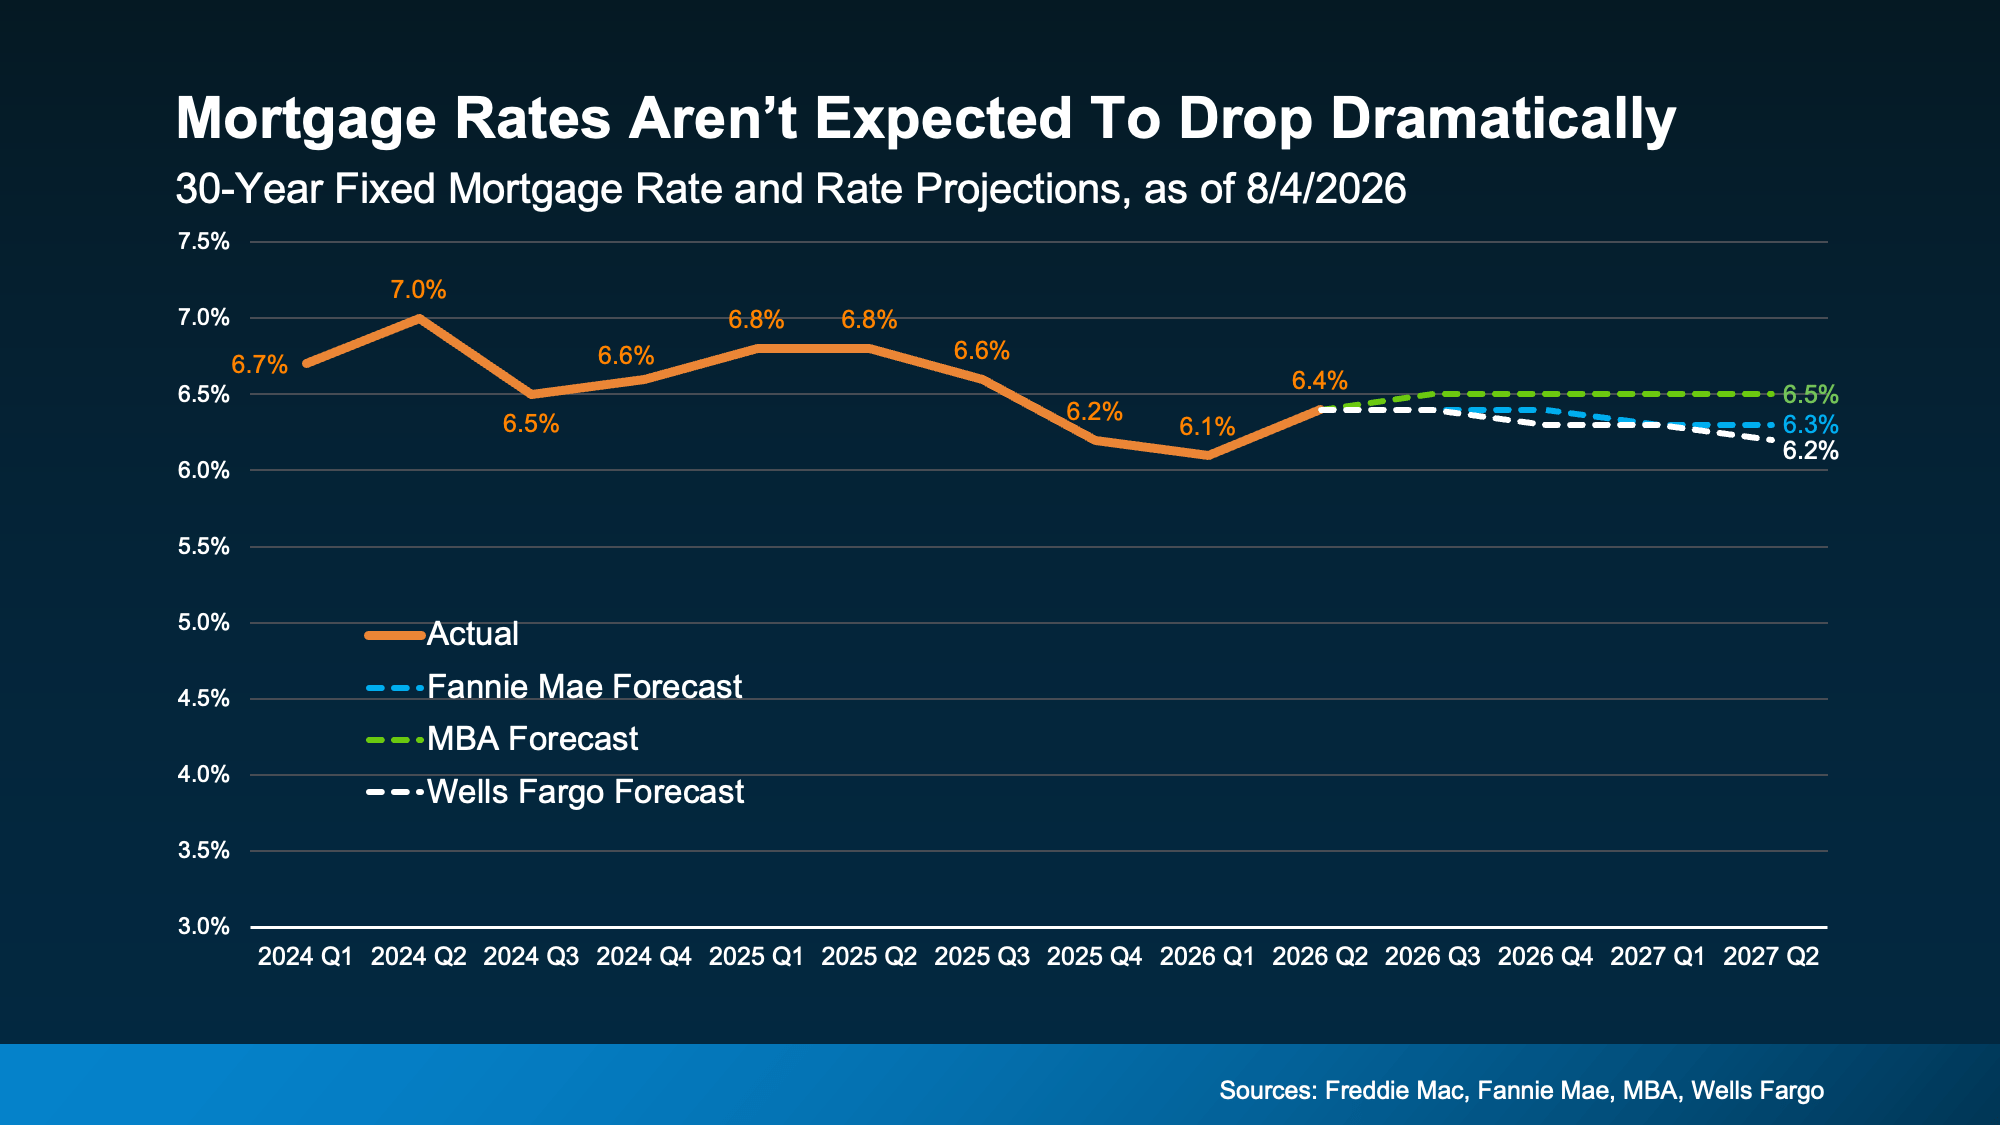
Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren’t pointing toward the kind of dramatic rate drop many buyers are waiting for.
Could rates move a little? Of course. But if you’re holding out for a bigger drop, today’s forecasts suggest you may be waiting a lot longer than you expect.
2. Inflation Is Still Elevated – And That’s Working Against Lower Rates
One reason experts aren’t expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.
And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):
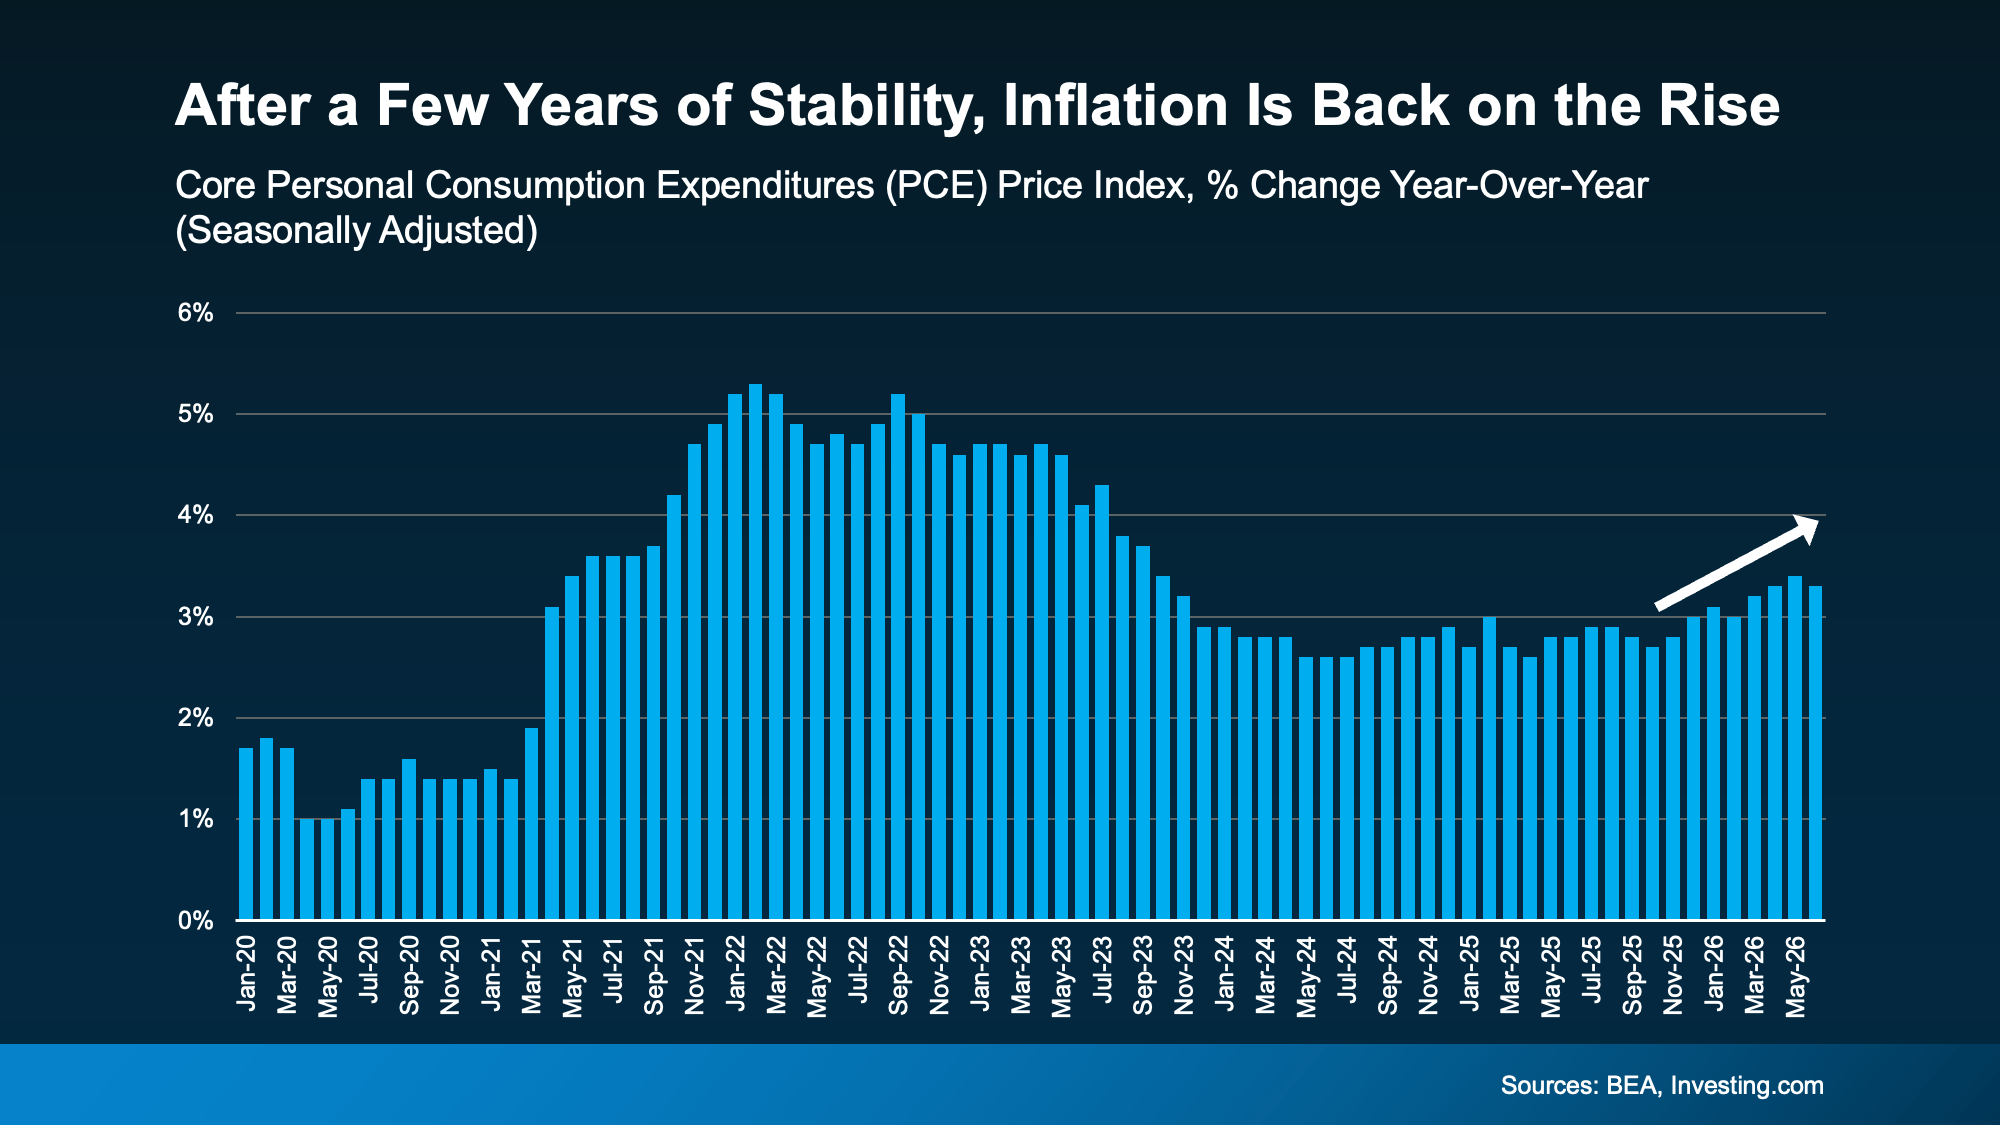
In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn’t in place today. That helps explain why experts aren’t forecasting the kind of meaningful decline so many buyers are hoping for.
3. Today’s Rates Aren’t High, They’re “Normal”
And this may be the biggest mindset shift of all. The reality is, while today’s rates may feel high compared to a few years ago, they’re not high. They’re normal.
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):
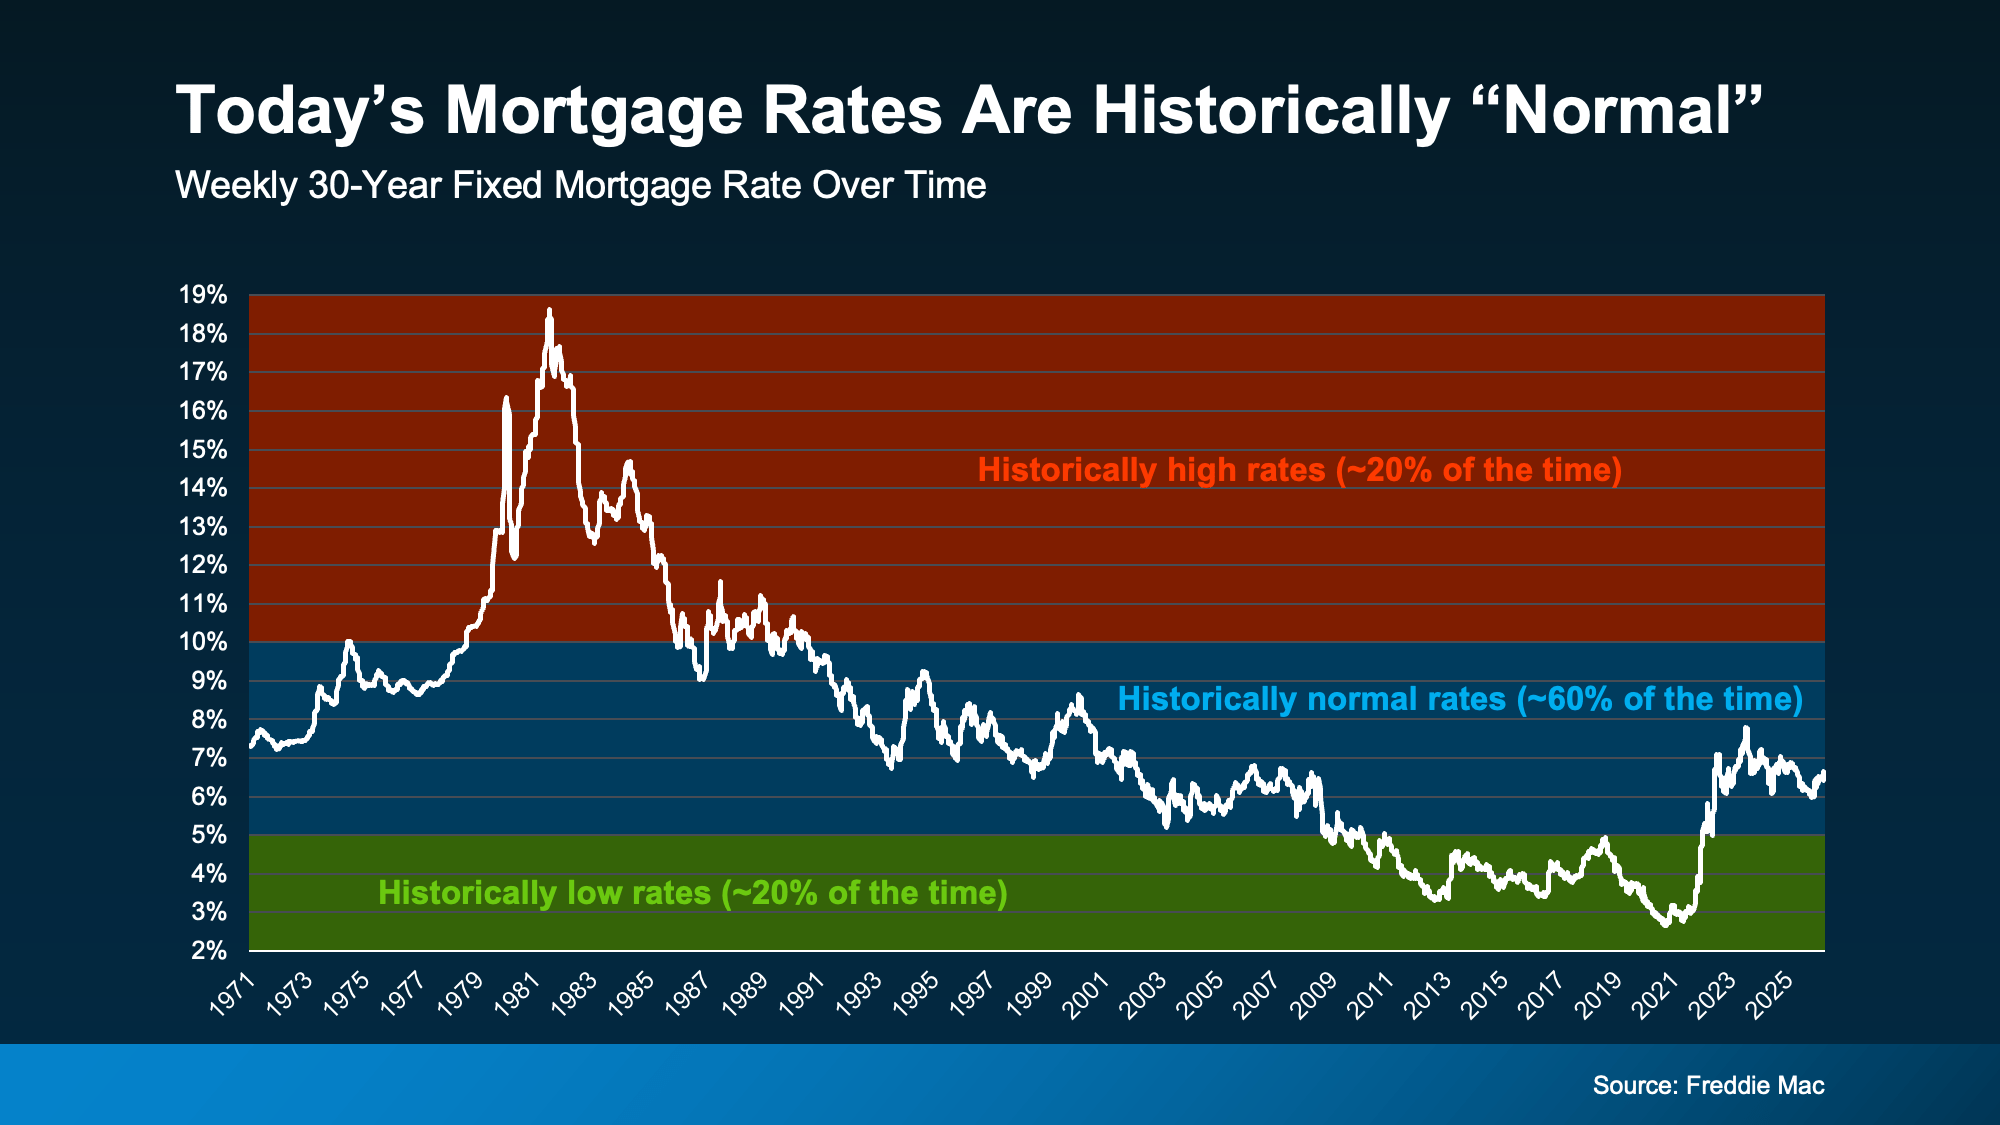
Now, this doesn’t suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.
So… What Should You Do Instead?
None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.
- Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.
- Ask about an adjustable-rate mortgage (ARM). If you don’t plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It’s not the right choice for everyone, but it’s worth asking a lender if it fits your plans.
- Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.
- Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.
The important thing is you shouldn’t assume waiting is your only option.
Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.
Bottom Line
If you’ve been putting your home search on hold because you’re convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.
Let’s connect so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer. Liz Norvelle (928) 458-4025.
Down Payments Are Smaller Than They’ve Been Since 2021
Saving for a down payment can feel like the hardest part of buying a home. And with affordability as tight as it’s been lately, it’s fair to wonder how anyone manages it right now. Here’s something you may not have seen coming.
Some people are getting their foot in the door with a smaller down payment.
According to Realtor.com, the typical buyer put down about $23,400 in early 2026 – that’s around $5,000 below what was typical the year before (a 19% drop year over year). That’s the lowest down payments have been since 2021 (see graph below):
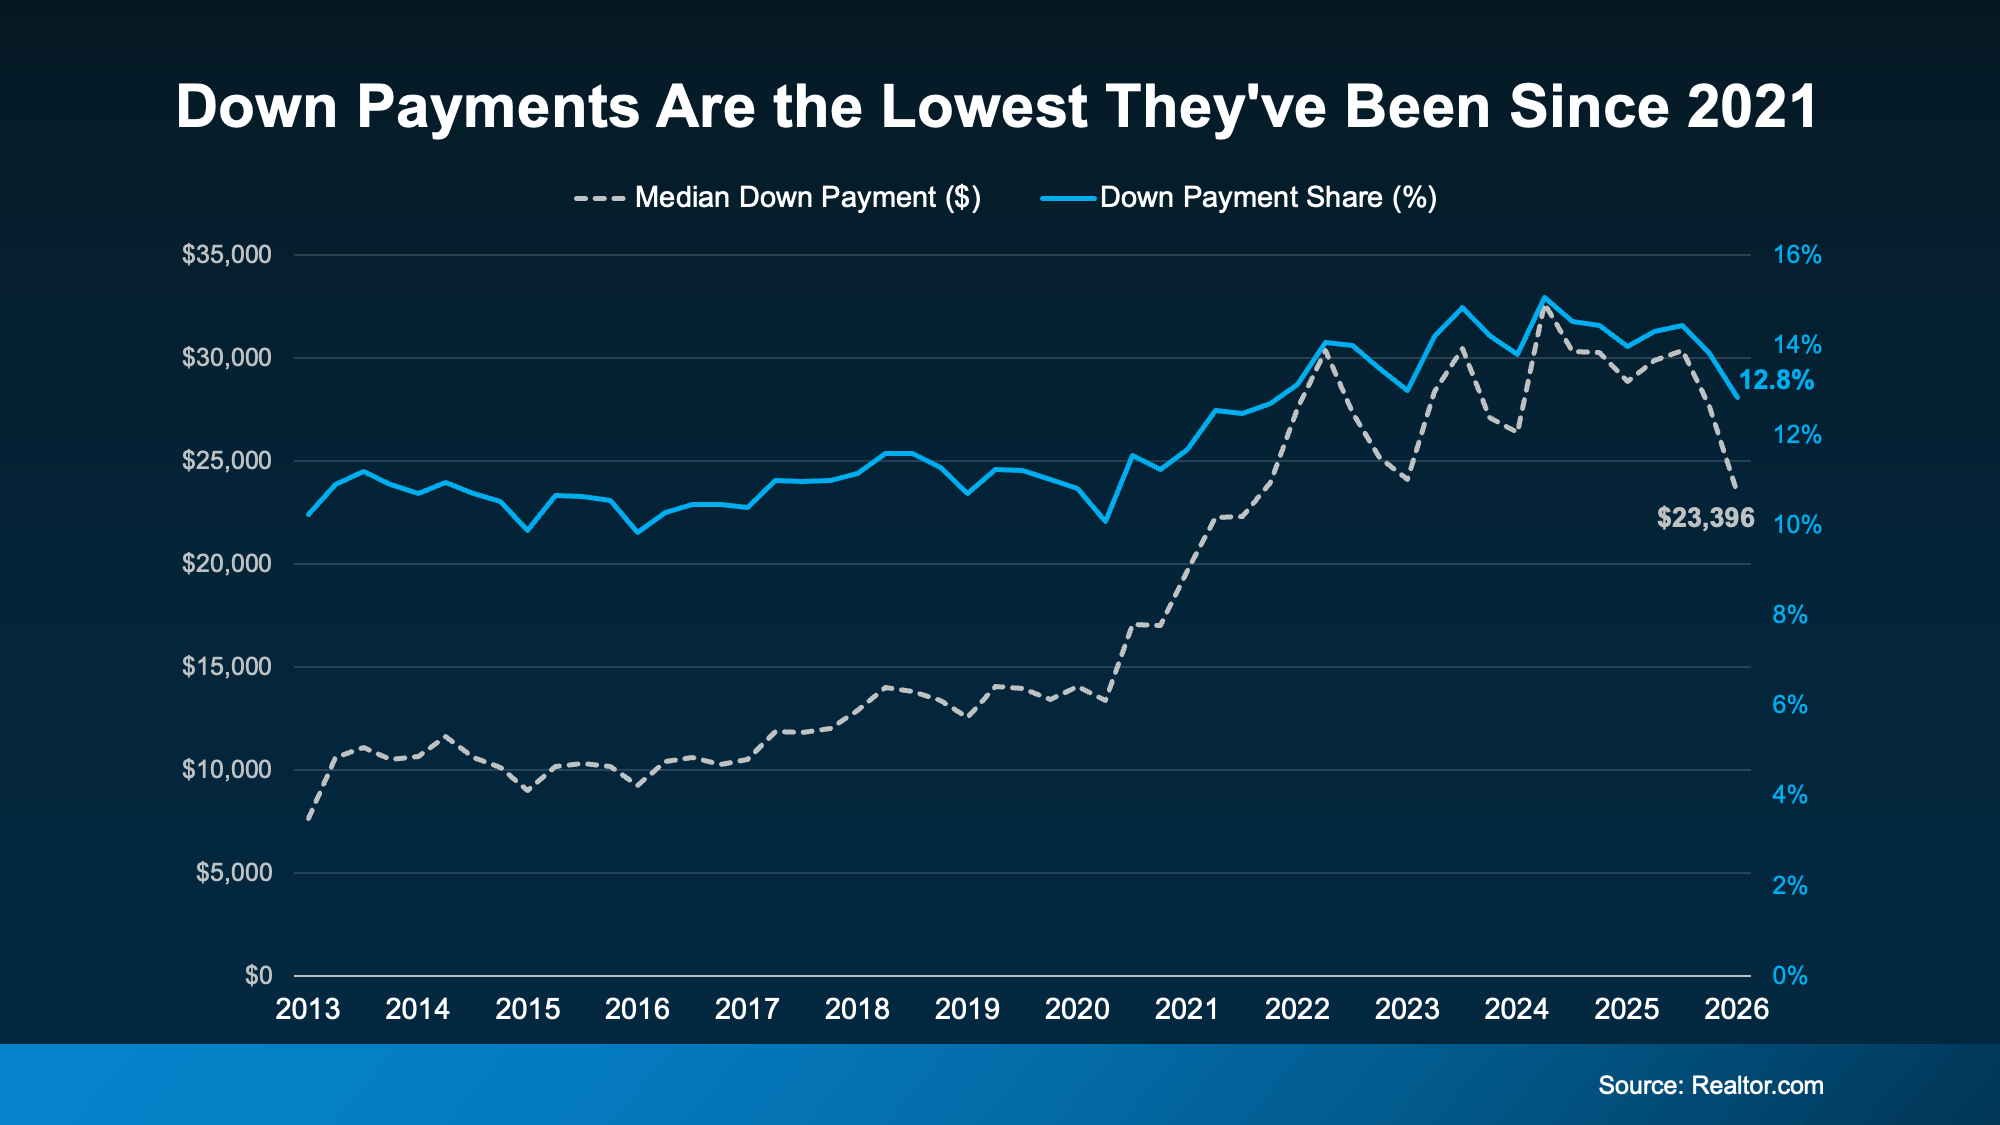
So why are buyers putting less money down, and how can you put less down, too? Here’s your answer.
Why Down Payments Are Getting Smaller
There are a few things driving the trend:
- Less competition between buyers. Part of it comes down to a more balanced market. With buyers facing less competition than they did a few years ago, there’s less pressure to put a big sum down just to stand out.
- More moderate home prices. Your down payment is a percentage of the purchase price. So, as price growth cools, the amount you need to put down may change too. In a lot of markets, prices have slowed or leveled off, and some areas are even seeing slight dips. That can translate into smaller down payments.
- Buyers opting for loans with lower down payments. More buyers are also turning to government-backed loans, like FHA and VA, which often need little or no money down. FHA loans have made up more than 24% of purchase mortgages for five straight quarters, and VA loans recently hit their highest share in over a decade, according to Mortgage Professional America.
But even a smaller down payment is still a significant chunk of cash, and saving it can be hard. So where does the rest come from? For many buyers, two things make the difference: programs built to help, and a hand from loved ones.
Help You May Not Know You Qualify For
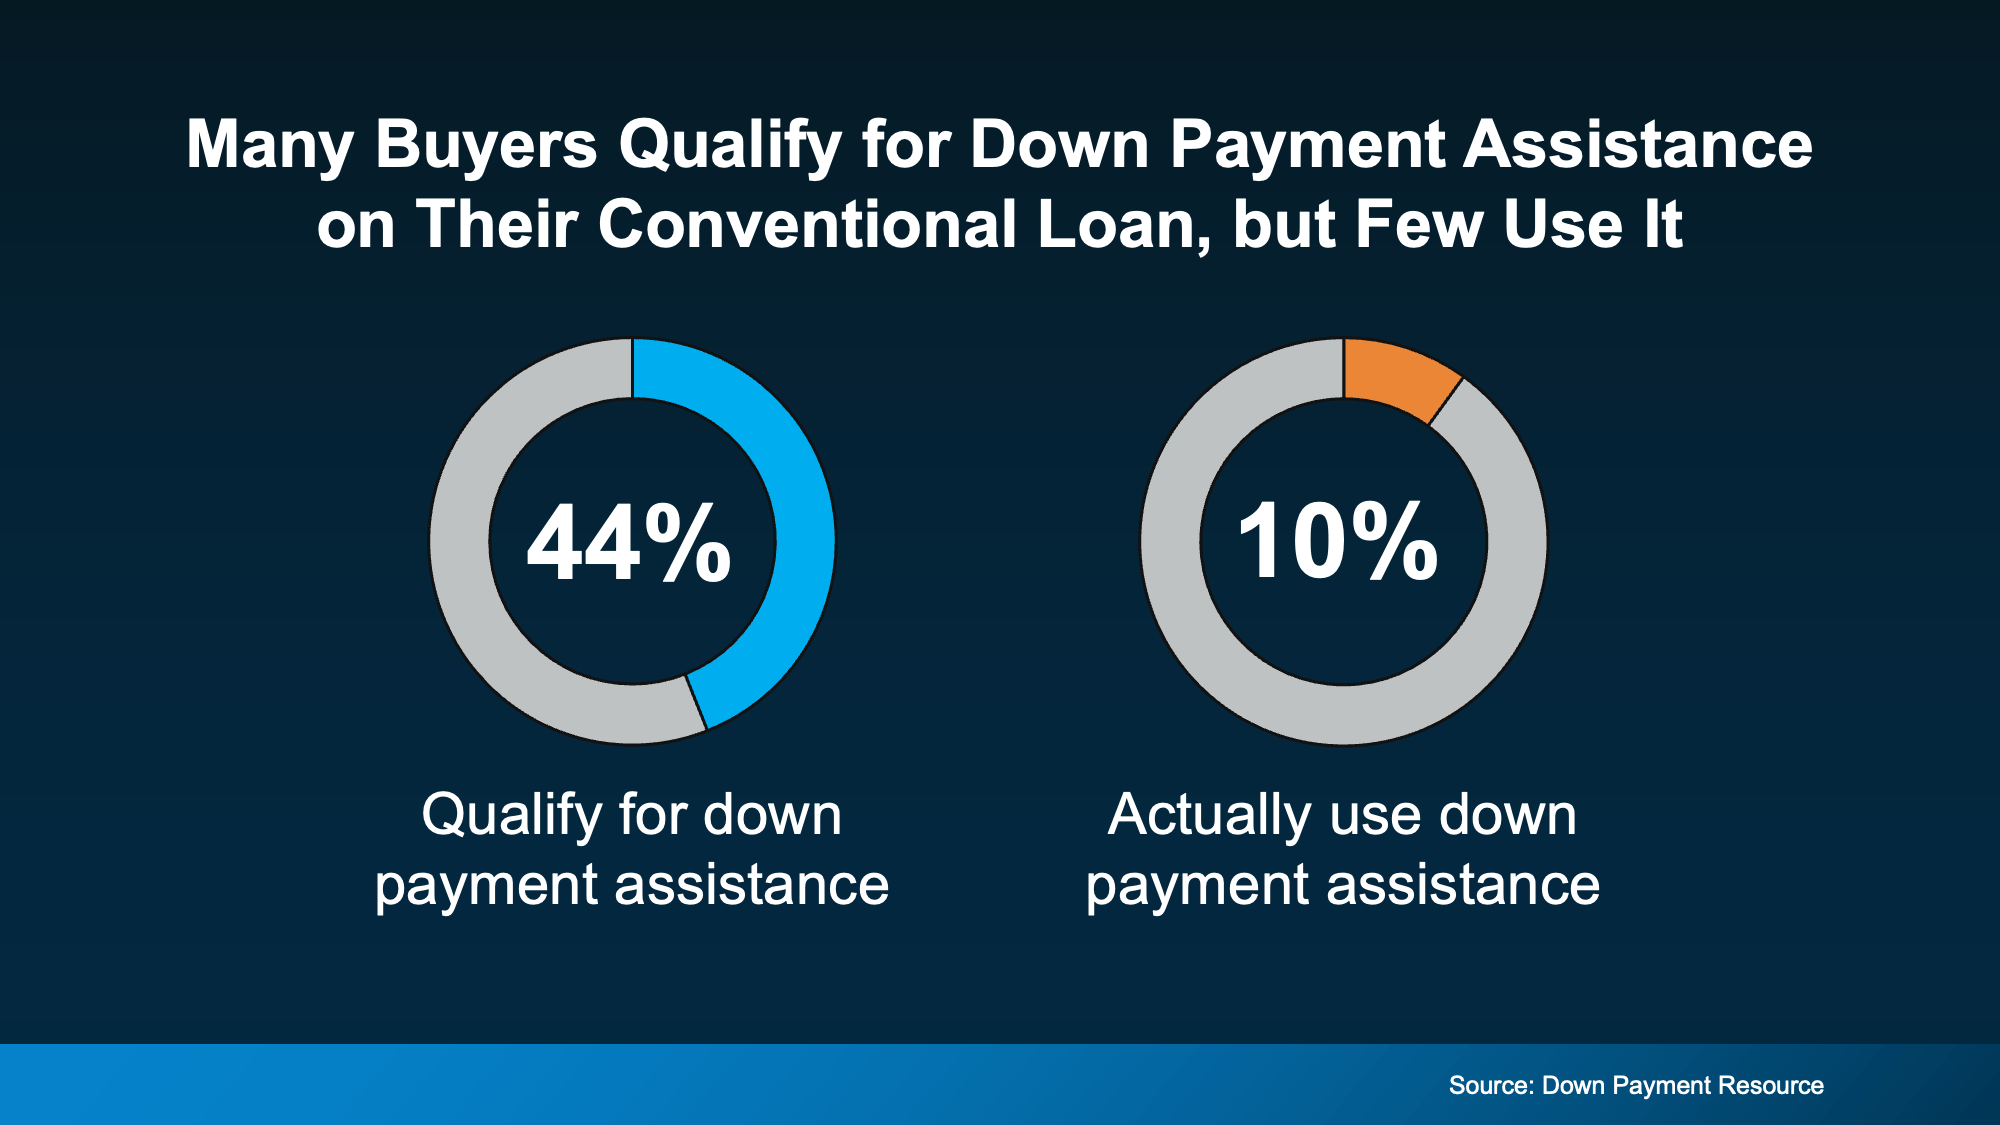
Down payment assistance is one of the most overlooked tools out there. Looking at the 10 largest U.S. metros, Urban Institute and Down Payment Resource found nearly 44% of recent buyers already qualified for a down payment program, but many of them closed on their loan without tapping the help (see chart below):
The options are broader than you might assume, too. According to Down Payment Resource:
- There are more than 2,600 down payment assistance programs available
- More than half (62%) are designed to help first-time buyers
- 38% have no first-time buyer requirement, so you may qualify even if you’ve owned before
- 62% are open to buyers earning $100,000 or more
A Boost from Loved Ones
For a growing number of buyers, help comes from closer to home. Research from Veterans United shows about 59% of parents have provided or plan to provide financial support to help their child buy a home.
That support most often goes toward the down payment, followed by help qualifying for a mortgage and covering closing costs. Chris Birk, VP of Mortgage Insight at Veterans United, puts it this way:
“For many families, helping a child buy a home has become less of an optional gesture and more of a practical response to today’s affordability challenges.”
If your loved ones are in a position to help, it can make a real difference in how soon you can buy.
Bottom Line
Down payments are smaller than they’ve been in years, and that opens the door for more buyers.
And with added help from assistance programs and a little help from loved ones, you may have more ways forward than you realized. Connect with a trusted lender to talk through your options.
(928) 458-4025
The Mid-Year Housing Market Update: Why Forecasts Changed in 2026
If the housing market feels confusing right now, you’re not alone.
Mortgage rates have risen. Home sales haven’t picked up like expected. And many buyers and sellers are wondering when things are going to feel easier or be more affordable.
The truth is: a lot changed over the first half of this year.
Back at the end of 2025, economists were forecasting a much stronger housing market for 2026. They expected mortgage rates to come down, affordability to improve more dramatically, and home sales to rebound.
But lingering inflation, economic uncertainty, and growing geopolitical tensions overseas pushed mortgage rates higher than expected. And because rates stayed elevated for longer, many buyers continued to hold off.
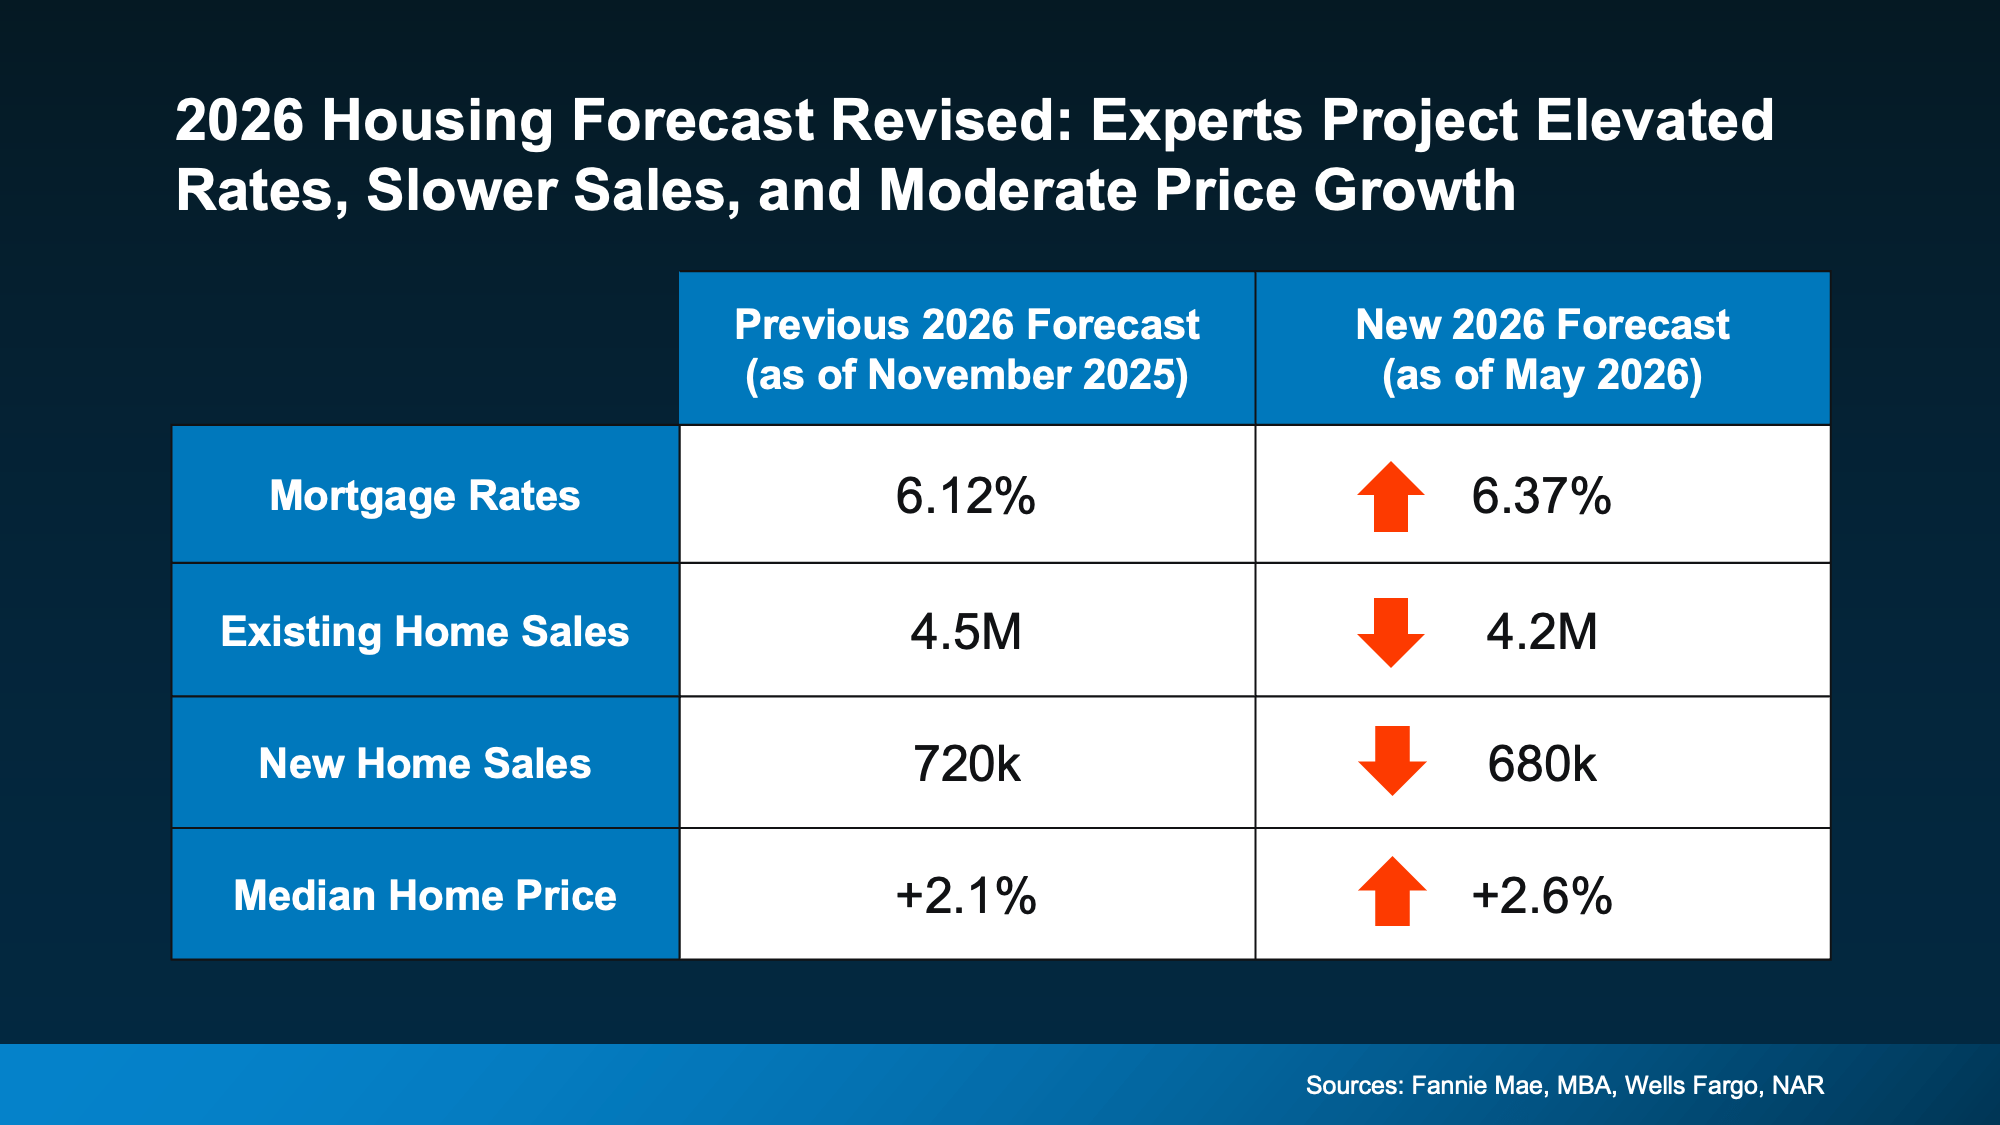
That’s why experts recently revised their housing forecasts for the rest of the year (see graph below):
So, what does this actually mean for you? Let’s break it down.
Mortgage Rates May Remain Elevated
While just about everyone wants mortgage rates to go back to the uppers 5s or low 6s we saw at the start of the year, as of right now, the experts don’t think that’s likely to happen this year.
Instead, forecasts have been updated from the low 6s they originally projected. Many industry organizations are saying rates will stay in roughly the mid 6s this year. The good news is, that’s still lower than rates were a year ago.
Of course, this is based on what we know today. If the conflict overseas comes to an end or inflation drops, this could change. But if you’re waiting for lower rates, it may not pay off in the way you expect.
Existing Home Sales Revised Lower
Back in late 2025, experts expected we’d sell an average of 4.5 million homes this year. Now? That’s dropped down a bit to 4.2 million.
That tells us something important: buyers are still hesitant because affordability remains challenging.
Higher mortgage rates have made monthly payments harder to manage, especially for first-time buyers. And that’s slowed the pace of the market compared to what was originally expected. But even though the forecast was revised down, we’re still expected to sell more homes than last year.
Once geopolitical tensions resolve and rates begin to settle down, many experts believe that group of buyers will be ready to jump back in. As Lawrence Yun, Chief Economist at NAR, explains:
“There is sizable pent-up demand that could be released into the market.”
There has already been a few glimmers of renewed hope lately. In recent months, pending homes sale have been improving month-over-month despite higher rates.
So, if you’re able to afford a home at today’s rates, it could still make sense to buy now. Because otherwise, if you wait, you’ll have more competition (and potentially fewer homes to choose from) when those others buyers jump back in.
New Home Sales Also Slowed
Builders also expected to have a stronger year. Earlier forecasts projected new home sales would top 700k in 2026. Now, economists expect we’ll be just shy of that number.
Again, mortgage rates are a major reason why.
But the upside for buyers is that builders may be even more motivated to sell. That means builder incentives, negotiation opportunities, and pricing flexibility may continue in many markets. So, if you live somewhere where there’s more new construction, this may actually be a bright spot for you.
Builders could be more ready to negotiate, and that gives you more leverage to get a better deal.
Home Prices Are Still Expected To Rise
This is one of the most important takeaways from the entire forecast. Even though sales activity is slower, on average, experts did not revise their home price forecast downward.
They still expect prices to rise nationally this year.
Why? Because while buyer demand has softened, the number of homes for sale is still relatively limited overall. That imbalance is helping support prices, even in a slower market.
Of course, conditions vary depending on where you live. Some markets are cooling more than others. But nationally, experts are still projecting steady price growth — not a major decline. And that should be a comfort whether you’re buying or selling.
Because sellers don’t want a major drop in prices. And while buyers may think they do, generally you feel better about a big purchase when it doesn’t depreciate right away.
Bottom Line
The housing market hasn’t rebounded as quickly as experts originally hoped. But that doesn’t mean it’s stalled.
Higher inflation and lingering economic uncertainty caused economists to revise their forecasts for this year. But importantly, when those two things settle down, many experts believe the market will regain its momentum.
So don’t see this revision in forecasts as a sign of trouble. See it as a temporary reaction to overall conditions and uncertainty.
If you want to know what’s happening in our local market, and what it could mean for your plans for the rest of this year, let’s connect.
(928) 458-4025
The Secret To Selling Fast, No Matter the Market
When you put your house on the market, you don’t just want it to sell. You want it to sell fast. But the thing is, nationally, it’s taking a little longer to sell lately. And that slowdown can feel frustrating if you want a fast process. Here’s what you need to realize.
In every market right now, there’s one clear exception:
Well-priced, well-presented homes are still selling, and it’s often faster than you’d expect.
If you can tap into that, you can still set yourself up to move quickly, too. Here’s how to get it done.
How Long It Takes To Sell Today
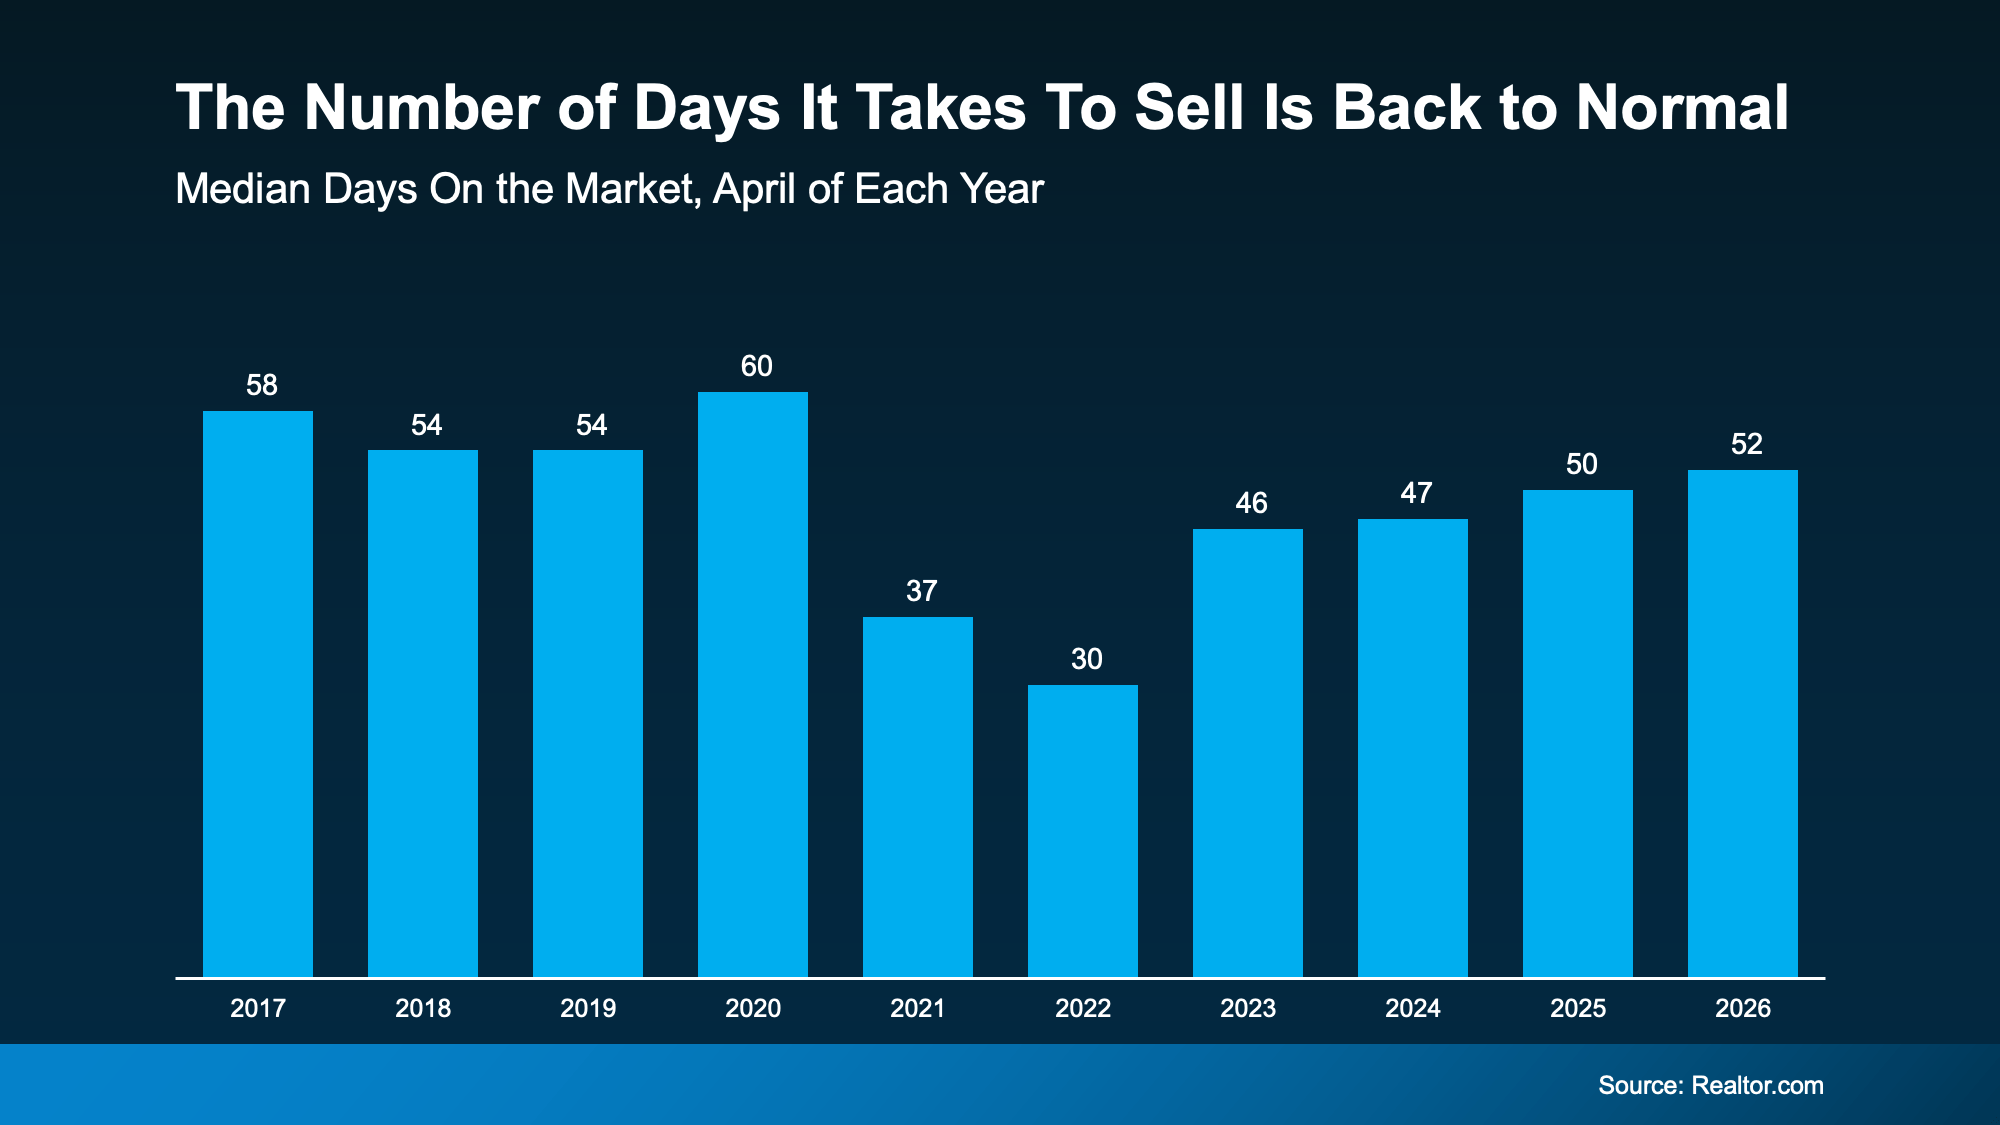
According to Realtor.com, homes are selling in about 52 days right now. That’s how long the process takes from the day it hits the market until closing day.
And while that may sound slow to you, it’s not slow. It’s normal.
That’s because it’s pretty much right in line with what it was during the last normal years in the market (see 2018-2019 in the graph below):
 It just feels slow when you’re eager to move – or when you think back a few years to when homes seemed to sell almost instantly.
But here’s what matters most. The market is normalizing. Not at a standstill.
This is the norm for timing from start to finish. You may have an accepted offer in hand even faster than this.
Markets Where Homes Still Sell Quickly, Even Now
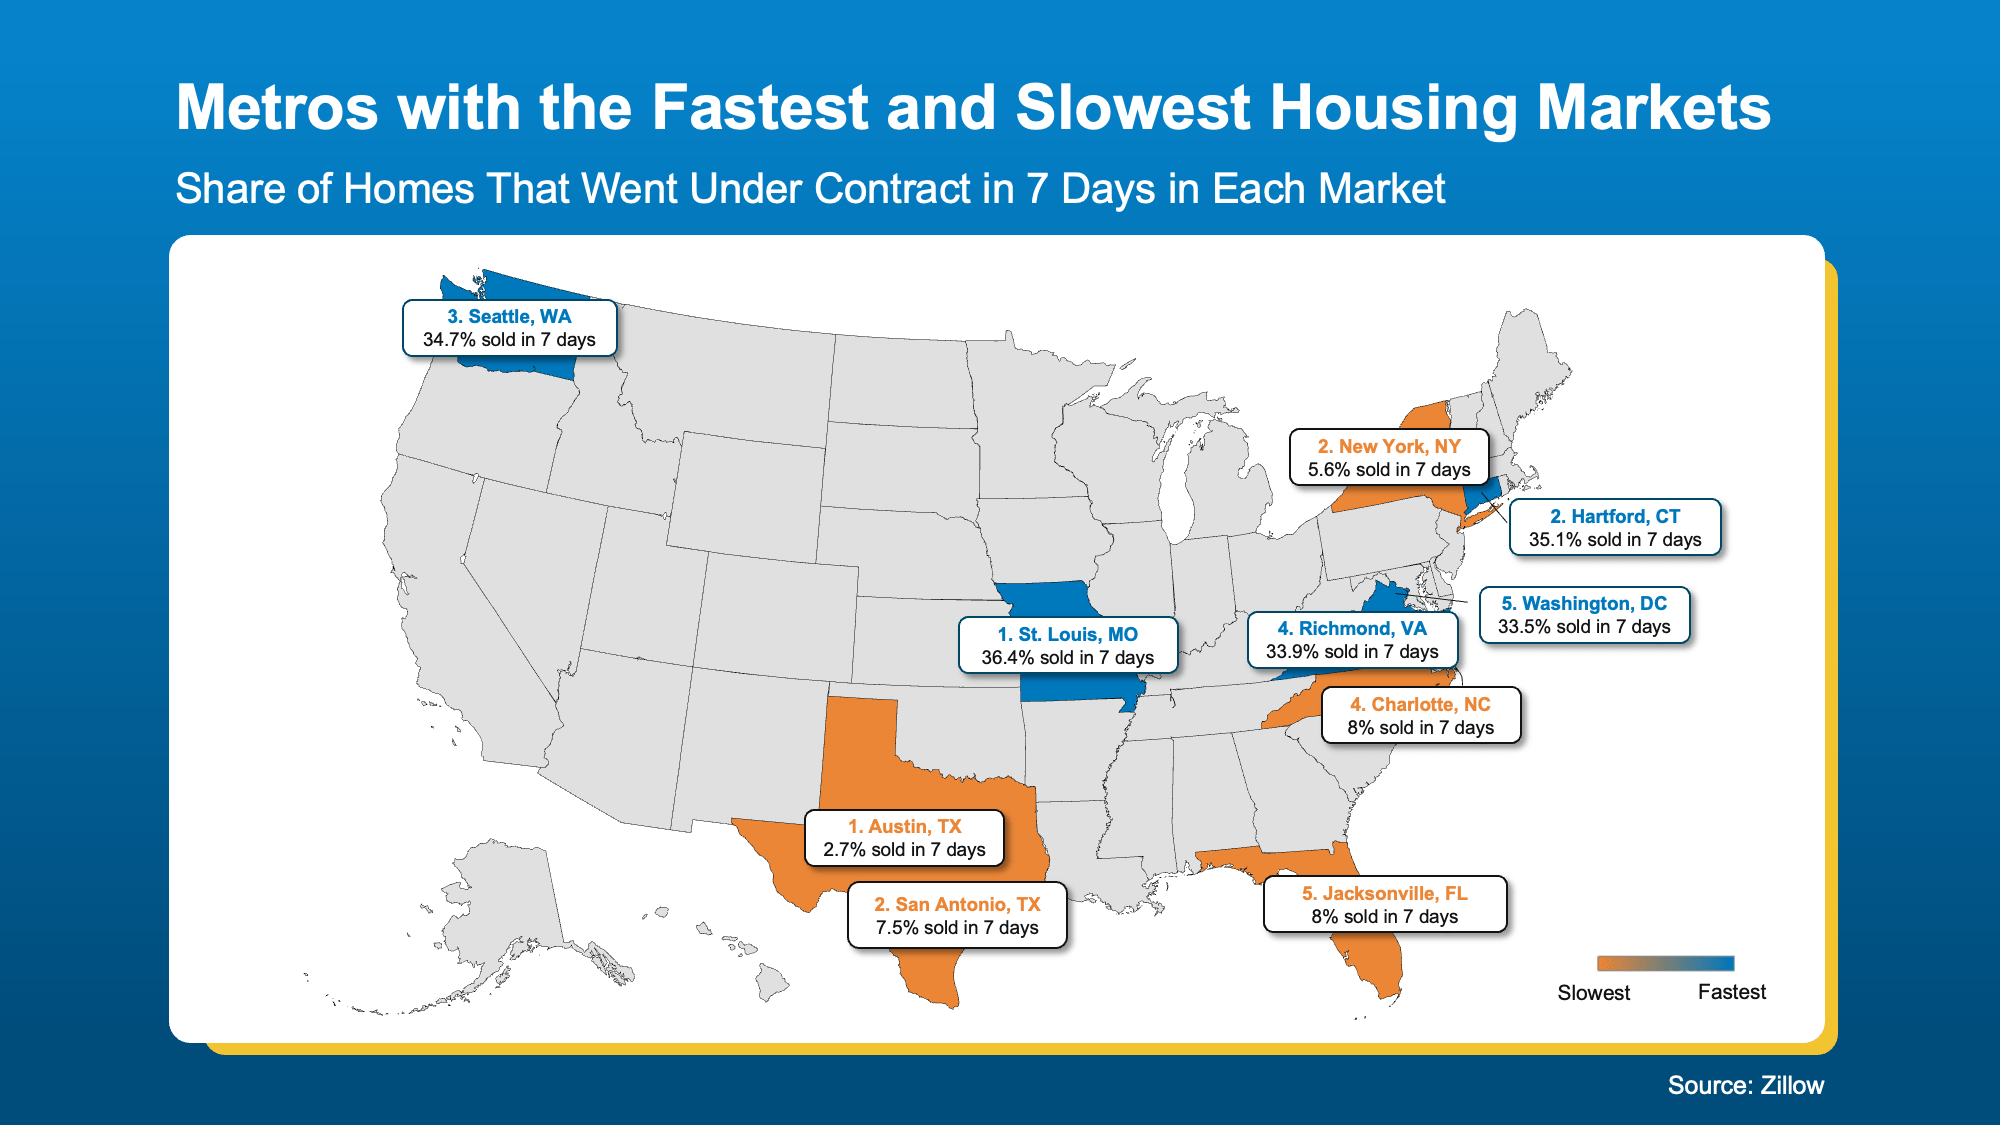
Zillow says the typical home will go “pending” or “under contract” in 19 days. Some homes even see it happen in as little as 7 days. It just depends on where you are – and how you prep your house.
So, don’t let the slowing pace of sales stress you out. Homes can still sell fast, if they’re positioned right.
Just to show you, here’s a quick look at some of the markets that are moving faster than the norm, according to Zillow (see map below). This’ll show you how different it can be based on where you live.
 The key things you need to remember when looking at this visual:
- It varies a lot based on where you live. Within the same state, individual neighborhoods or pockets may sell much faster than the norm.
- Even in slower moving states, you can still sell quickly. As the map shows, in those places there are still homes that go under contract in as little as a week.
So don’t worry about if your state made either list. As Orphe Divounguy, Senior Economist at Zillow, says:
“The cream of the crop is still selling fast, even in markets that have slowed considerably. . .”
The Big Reasons Some Homes Sit, and Some Sell Fast
And here’s the big secret. While location can definitely play a role, it’s not just about location. It’s about strategy.
Today’s buyers are paying attention to condition. They’re comparing photos, upgrades, layout, location, and price. And they’re choosing homes that feel move-in ready and well worth the value.
The homes that check those boxes? They’re not sitting for long – no matter where they are.
As the Wall Street Journal (WSJ) explains:
“. . . some homes are still flying off the shelves. These houses are often in the Midwest or Northeast, where the lack of new construction keeps a lid on supply. Certain homes in other markets are selling quickly, too, often when a home is move-in ready.”
Because in any market – hot or not – if a home is overpriced, needs too much work, or just doesn’t meet current buyer expectations, it’s not going to sell.
In this market, the sellers who win are the ones who get real about their house. They’re honest about how their home compares to other listings, realistic about price, and they work with an agent who truly understands today’s market and what it takes to sell.
When your agent knows how to price strategically, spotlight the strengths of your home, and move quickly when the market gives clear signals, that’s when the results follow.
Bottom Line
Today’s housing market rewards the right strategy. Because even in a slower area, the homes that are priced realistically and positioned well are still selling – sometimes faster than you may expect.
Let’s connect if you’re ready to make yours one of them. Call Liz Norvell at (928) 458-4025.
Wondering If You Should Still Buy a Home Right Now? Here’s What To Keep in Mind.
With economic headlines, global events, and near constant talk about affordability, you may be wondering if this is the right time to move. But here’s what you need to remember.
While recent events do have some impact on the housing market, they don’t take buying off the table. You just have to use a different strategy.
Mortgage Rates Have Been Up Slightly – Here’s Why
After trending down for most of 2025, mortgage rates have been higher again for over roughly a month now. And experts say it’s a result of what’s happening overseas and in the broader economy. As Mark Fleming, Chief Economist at First American, explains:
“Mortgage rates have recently moved higher, driven by geopolitical uncertainty and rising energy costs that are contributing to inflation concerns.”
But what does that really mean for you? Should you wait for everything to settle back down before you buy a home?
The short answer is no. You don’t have to wait.
Your Window To Buy Didn’t Close
It’s true that a month or so ago, when rates were just shy of 6%, buying felt a bit more affordable. And now that rates are hovering around the mid-6s, monthly payment costs are higher.
But zoom out for a second.
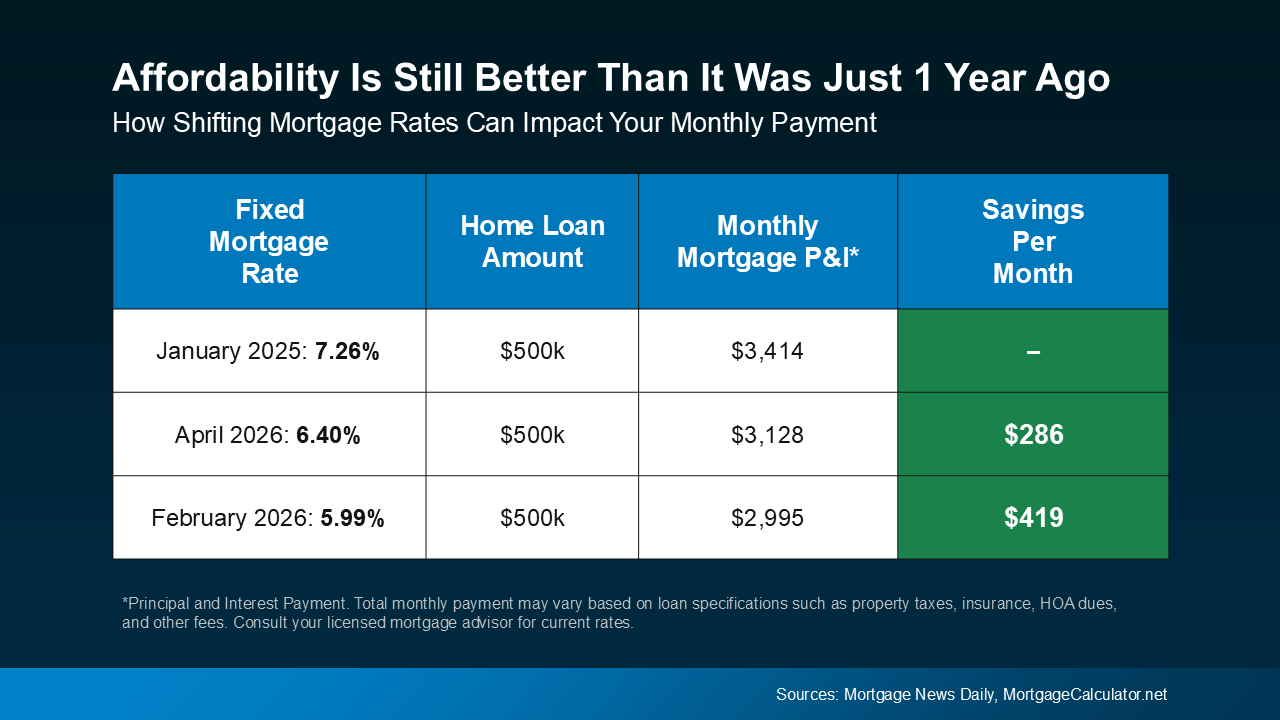
Let’s say you’re taking out a loan for $500k. Even with rates in the mid 6s, you’re still saving roughly $300 on your monthly payment compared to buyers who made their purchase early last year.
That means this recent increase in rates hasn’t erased the progress we’ve seen. Buying is still more affordable than it was just one year ago (see below):
 Sure, your monthly payment would’ve been a little less expensive a few weeks back. But hindsight is always 20/20.
The goal moving forward shouldn’t be to perfectly time the market. Things change too quickly for that. Instead, the real goal is to make the best decision you can based on where things are today. And the best advice anyone can give is: brace for volatility.
When It Comes To Rates, Expect the Unexpected
Mortgage rates are going to continue to be move around in the weeks or months ahead as new information and economic reports come out.
Try to remember, you can’t control global events or where rates go next week (or even next month). But you can control how you prepare. If you do that, it becomes less about the headlines, and more about your situation.
If You Want or Need To Move, You Still Can
The simple truth is, if you want or need to move, you still can.
Some buyers are choosing to move forward right now because their needs haven’t changed. A growing family, a job relocation, a lifestyle shift – those things still matter.
And for buyers who do decide to move forward, there are ways to make it work.
For example, you could explore options like adjustable-rate mortgages (ARMs) to get a lower rate upfront. That may or may not be the right fit for you, but it highlights an important point: there are strategies that can help you move, even now.
What matters most is having a plan.
And working with the right agent and lender is a big part of that. With expert help, you’ll:
- Understand your budget and what the math looks like at today’s rates.
- Explore your financing options, including ARMs and assistance programs.
- Have trusted guidance from experts who’ll keep you up to date throughout the process.
Bottom Line
Even though there’s some uncertainty, that doesn’t mean you’re out of options.
If you need to move, you still can. Let’s connect so we can explore all your options and make your move happen.
(928) 458-4025
One Key Sign We’re Not Headed for a Wave of Foreclosures
Foreclosures are ticking up. And that may make your mind jump straight to thoughts of 2008 – specifically to what happened to the market during the housing crash. So, let’s do exactly what your brain already wants to do, and see if there’s any connection there.
The simple truth is foreclosure filings are rising. But they’re nowhere near crisis levels. And that’s not where they’re headed either. Here’s why.
Take a look at serious delinquencies – loans where the homeowner is more than 90 days late on their mortgage payments.
While those have increased slightly, data from the New York Fed shows they still remain low. And they aren’t anywhere close to levels seen when the market crashed (see graph below):
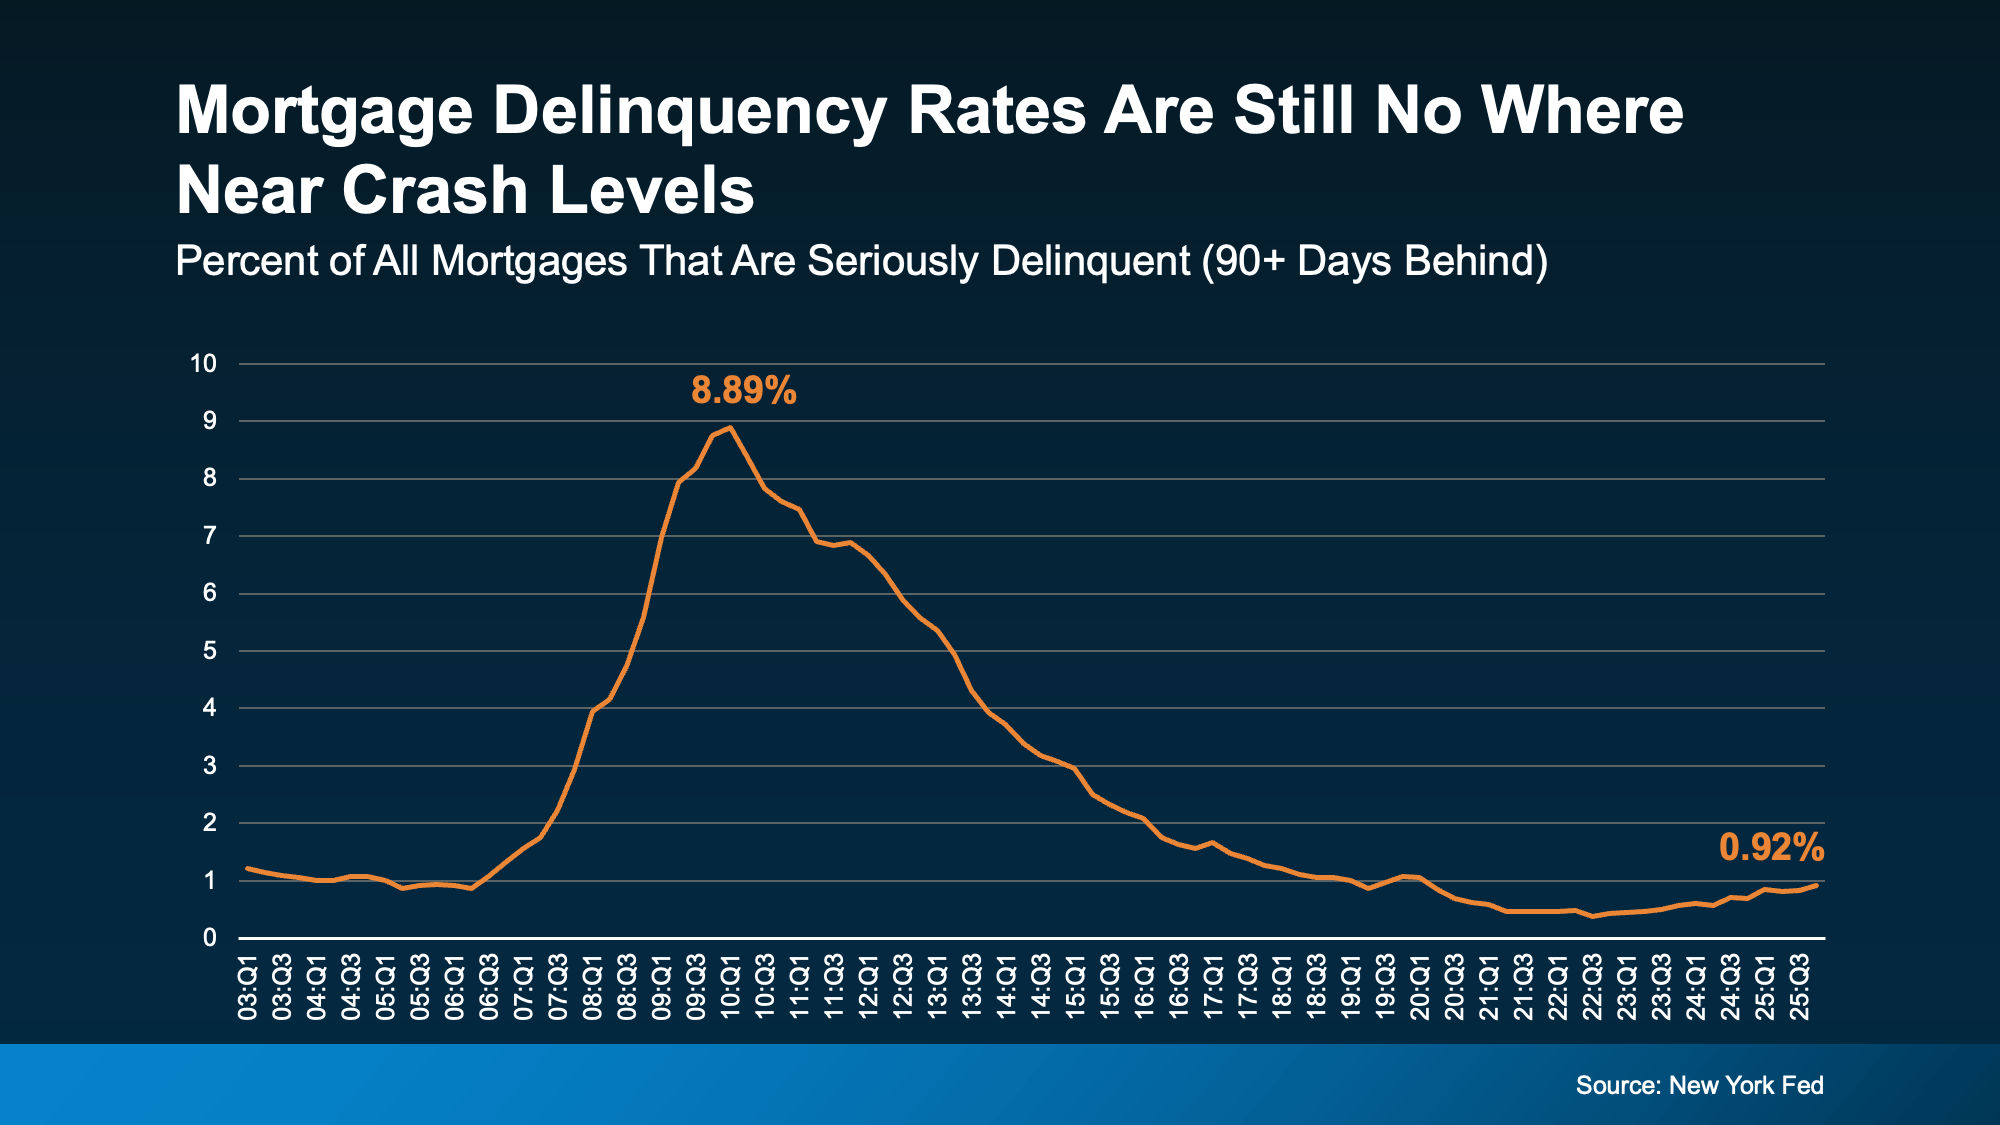 Right now, about 1% of mortgages are seriously delinquent. That’s only 1 in 100.
In the years around the crash, they were up around 9%. That’s 1 in 11.
That’s a big difference.
And it’s important to remember not all delinquencies even become foreclosure filings. Some homeowners who are falling behind will work out repayment plans with their banks and lenders because banks don’t want to see a wave of foreclosures either.
That’s why foreclosure numbers are even lower than delinquencies. ATTOM shows only 0.3% of all homes are currently going through a foreclosure filing. And those won’t even all go to a full foreclosure. That’s not a wave. That’s a ripple at most.
If People Are Falling Behind on Payments, Why Aren’t There Even More Foreclosures?
And maybe you’re wondering, if people are struggling financially, why aren’t there more foreclosures? Here’s the easiest way to answer that.
When households feel financial pressure, they tend to prioritize their mortgage payment above almost everything else. Because the last thing they want to lose is their home.
Data from the New York Fed shows serious delinquencies have risen more for credit cards and auto loans (the blue and green lines). But mortgage delinquencies and home equity lines of credit (borrowing against the value of your home) aren’t seeing the same big uptick (the yellow and orange lines). They’re a lot more stable overall.
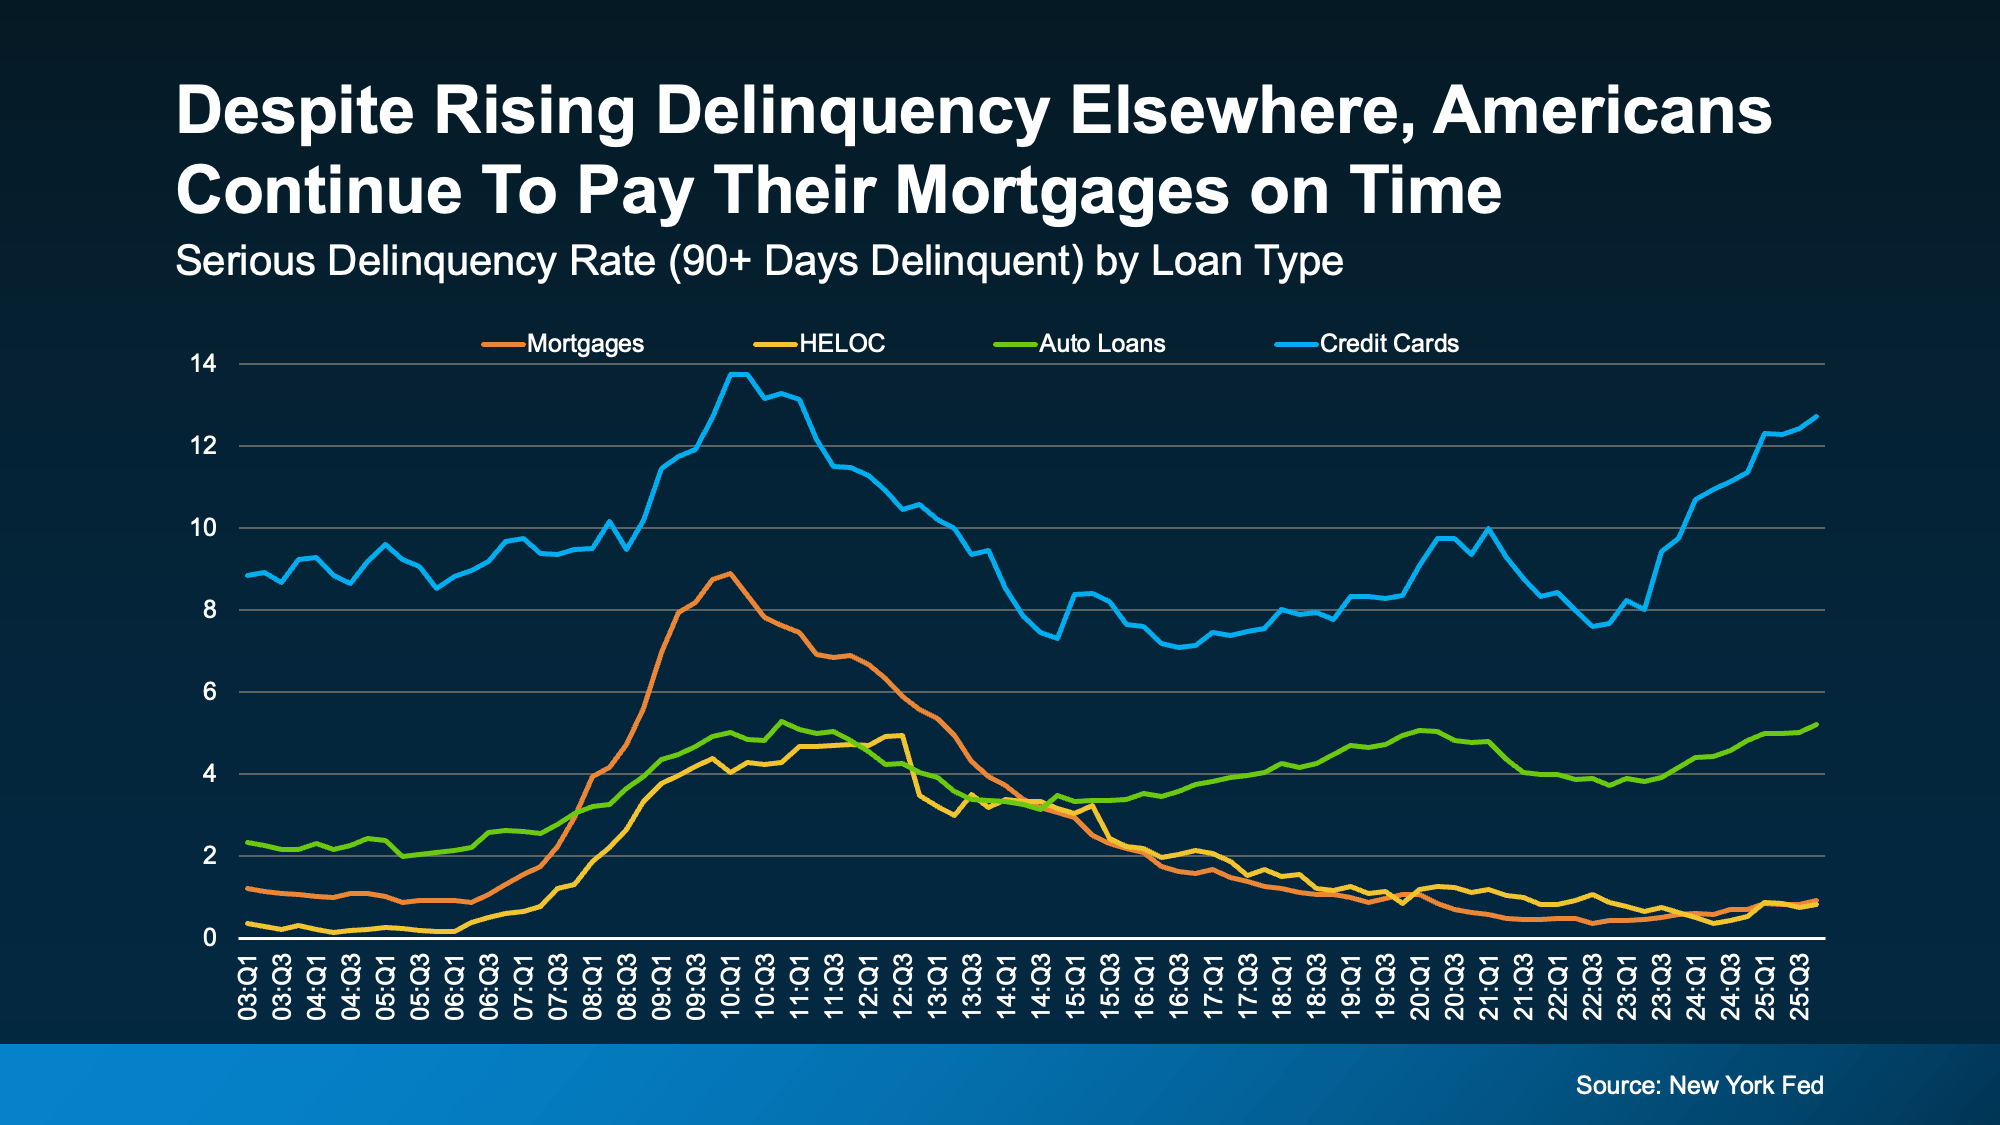 In other words, people may fall behind on other debts, but they fight hard to keep their homes. And, in today’s housing market, they’re also in a strong equity position to do so.
Home Equity Changes Everything
Many people have built significant equity over the past several years. And that creates options. As Daren Blomquist, VP of Market Economics at Auction.com, explains:
“Distressed homeowners… many times they still have equity in their homes. There’s an opportunity for them to sell that home, avoid foreclosure, and walk away with equity.”
That’s a major difference from 2008. Back then, many homeowners owed more than their homes were worth. And selling wasn’t an easy solution. Today, for many people, it is. And even in situations where equity isn’t enough, homeowners are encouraged to contact their loan servicer early to explore alternatives to foreclosure.
Bottom Line
Are foreclosure filings rising slightly? Yes. Are they anywhere near crash territory? No. And homeowners today have far more equity and flexibility than they did during the crash.
If you’re concerned about what you’re seeing in the headlines, the best move isn’t panic, it’s perspective. And the data right now says this isn’t 2008 all over again.
Inventory Is Making a Comeback in 2026
After a long stretch where buyers were competing for too few homes, inventory has made a comeback over the past year. And depending on where you live, that’s opening up your options in a meaningful way.
According to Realtor.com, the number of homes available for sale in January was the highest it’s been since 2020. Here’s why that’s such a big deal. Getting back to pre-pandemic levels signals a slow and steady return to what’s typical:
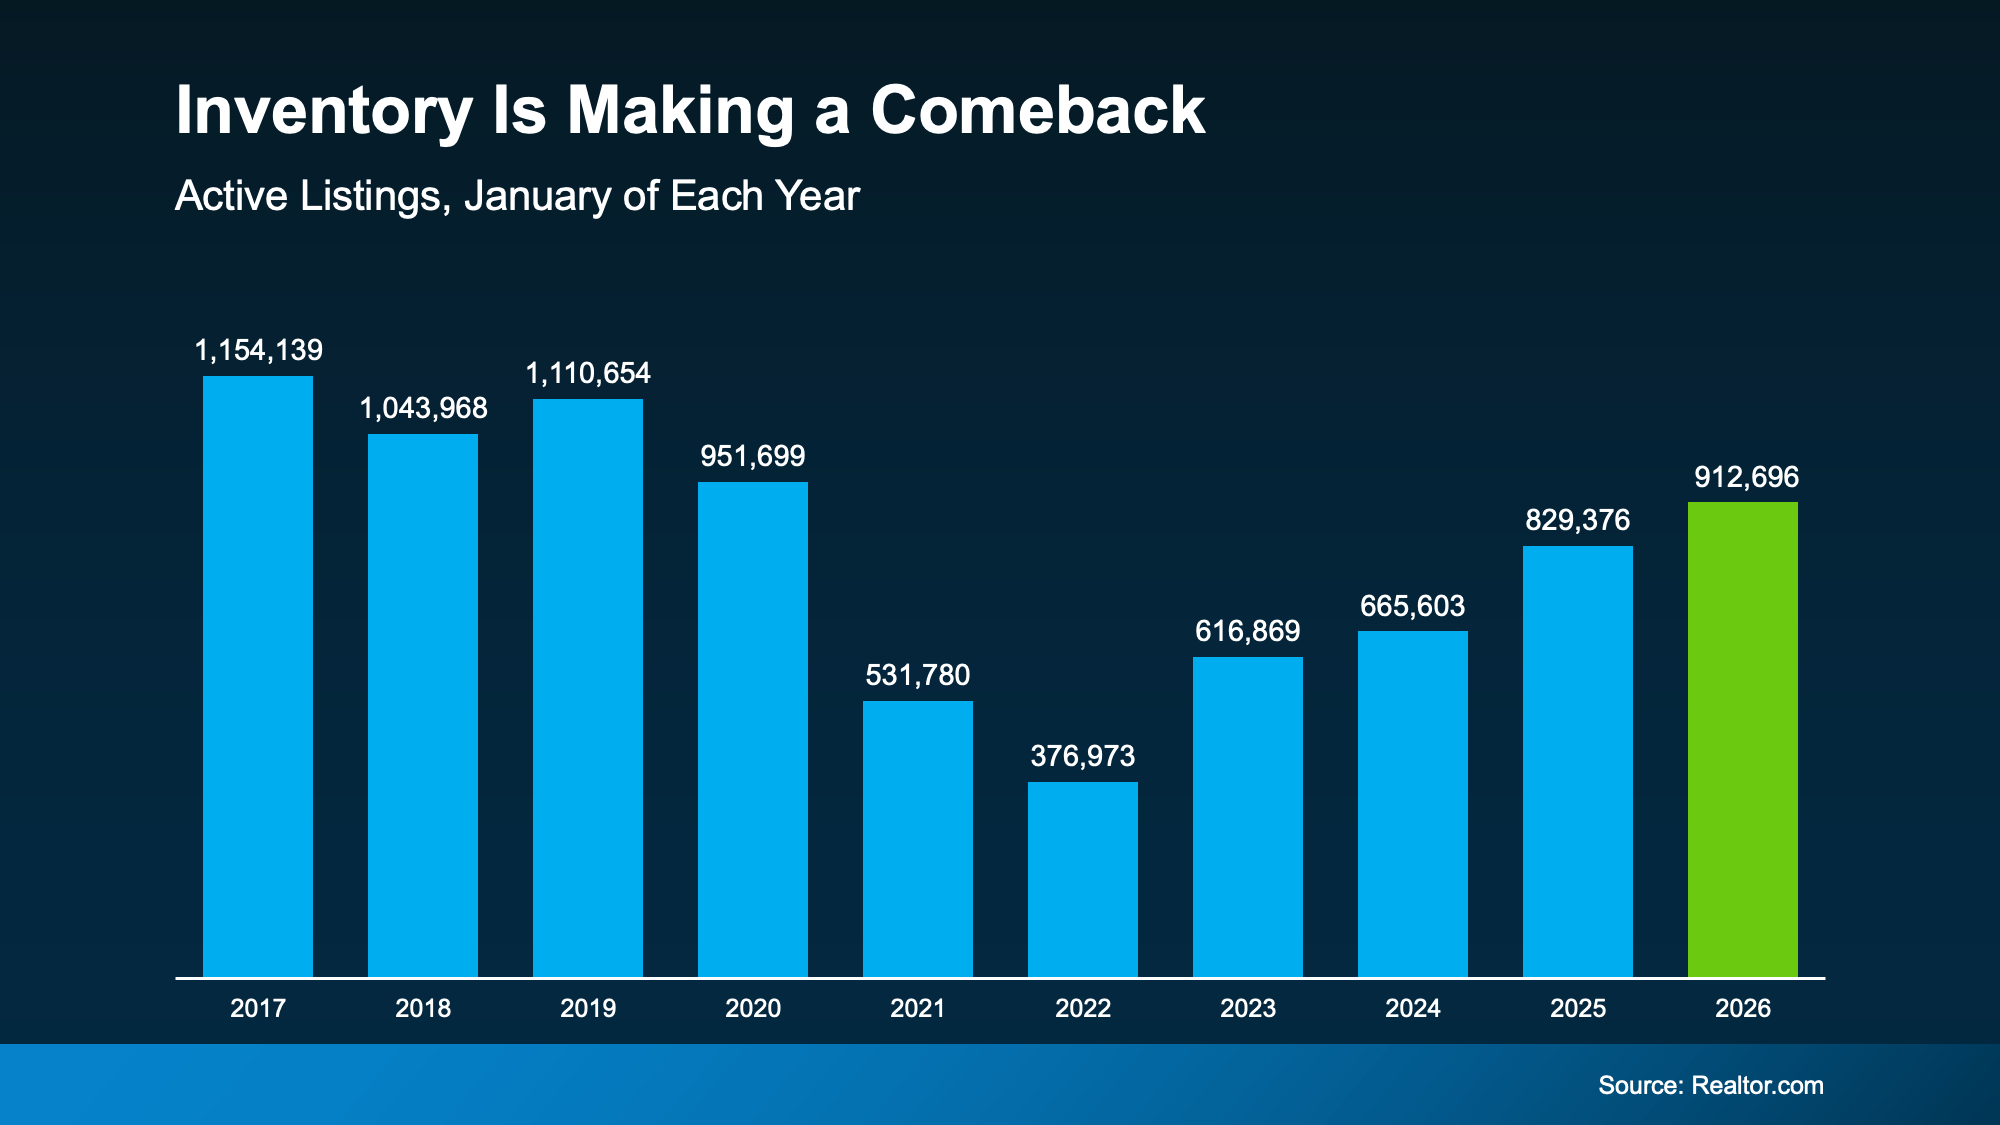
Now, it’s worth noting, nationally we’re not there yet – and having more inventory improving won’t suddenly “fix” the market. But the growth we’ve seen lately still changes how competitive the market feels.
- When there are more homes for sale, buyers gain time, options, and leverage.
- When there aren’t, the pressure ramps up quickly.
In the years since 2020, there weren’t enough homes for sale, and that made the market feel different. Rushed. Stressful. Intimidating.
But now it’s finally getting better.
A Growing Portion of the Country Is Getting Back to Normal
Depending on where you live, inventory growth is going to vary. Some places are bouncing back faster than others. According to Lance Lambert, Co-Founder of ResiClub, in January 2025, just a little over one year ago, only 41 of the 200 largest metros were back to normal inventory-wise.
But around the end of year, almost half (90) of the largest 200 metro areas were back at or above typical levels. That’s a big improvement in roughly a year. And it’s not done yet.
Inventory Is Expected To Keep Growing
Looking ahead, forecasts suggest the number of homes for sale could rise another 10% this year, which means even more markets should join the list of places where supply has rebounded.
Here’s a graph that shows what an extra 10% would do for the market this year. You can see that projected growth (shown in the dotted line) hits inventory levels seen in 2017-2019 by roughly this fall (the gray lines). That means we may reach normal by end of year, nationally:
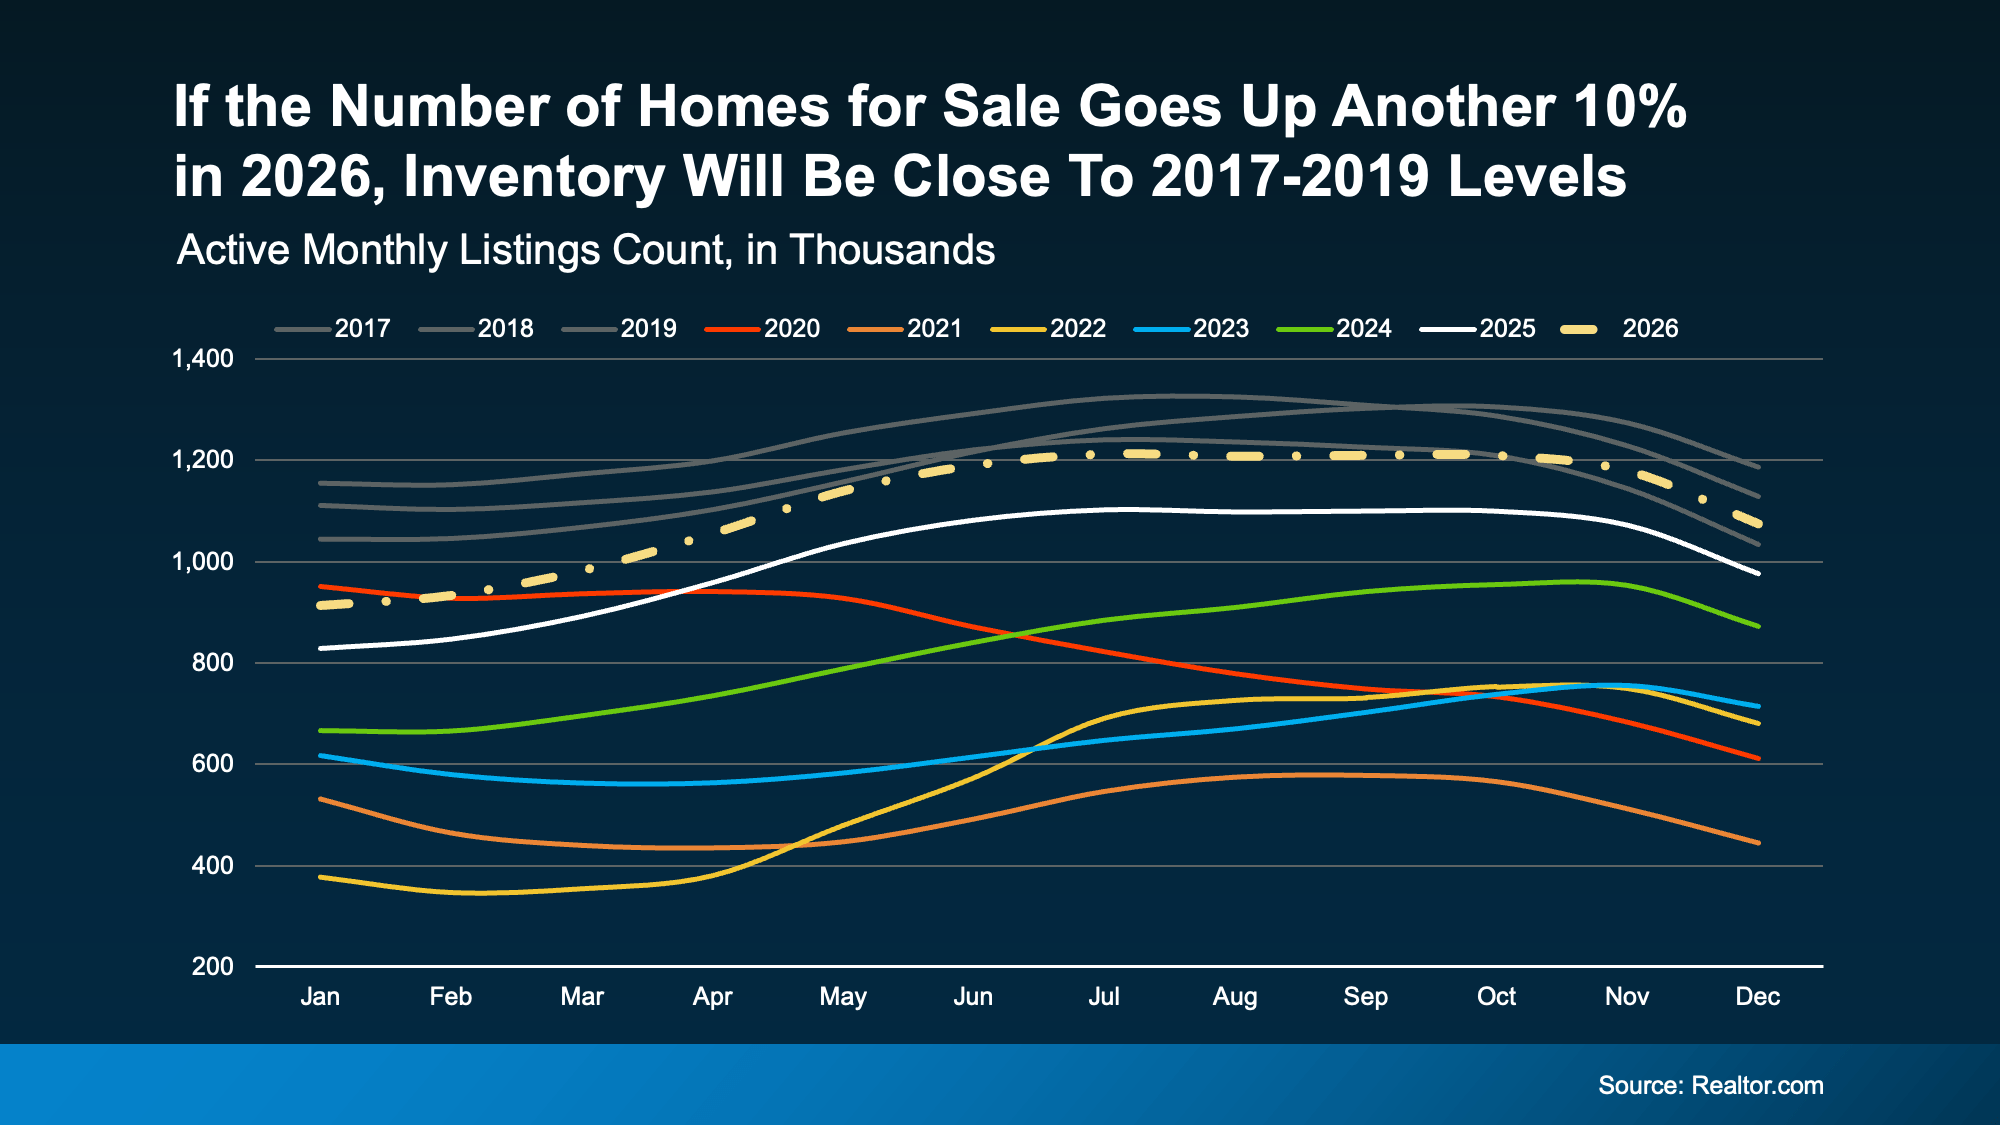
And that changes your home search in a good way. As Hannah Jones, Senior Economic Research Analyst at Realtor.com, puts it:
“. . . housing market conditions are gradually rebalancing after several years of extreme seller advantage. Buyers are beginning to see more options and modest negotiating power as inventory improves . . .”
In other words, the market is starting to work with buyers again — not against them.
Bottom Line
Inventory isn’t fully back to normal everywhere. But it’s moving in the right direction. And, in some areas, it’s already there.
If you’ve been waiting for a moment when you have options and a little breathing room, this is the strongest setup buyers have seen in a long time.
If you want to know what’s happening in our local market, let’s talk.
Liz Norvelle
(928) 458-4025
Not Sure If You’re Ready To Buy a Home? Ask Yourself These 5 Questions.
But here’s what you need to remember. While housing market conditions are definitely a factor in your decision, your own personal situation and your finances matter too. As an article from NerdWallet says:
“Housing market trends give important context. But whether this is a good time to buy a house also depends on your financial situation, life goals and readiness to become a homeowner.”
So, instead of trying to time the market, focus on what you can control. Here are a few questions that can give you clarity on whether or not you’re ready to make your move.
1. Do you have a stable job?
Buying a home is a big commitment. You’re going to take out a home loan stating you’ll pay that loan back. Knowing you have a reliable job and a steady stream of income is important and will give you peace of mind for a purchase so large.
2. Have you figured out what you can afford?
If you have a reliable paycheck coming in, the next thing to figure out is what you can afford. This depends on your budget, spending habits, debts, and more.
At this point, it helps to talk with a trusted lender. They’ll be able to tell you about the pre-approval process and what you’re qualified to borrow, current mortgage rates and your approximate monthly payment, closing costs, and other expenses you’ll want to budget for. That way, you have a good idea of what to expect.
3. Do you have an emergency fund?
As you crunch your numbers, you’ll want to make sure you have enough cash left over in case of emergency. Think about it. You don’t want to overextend on the house, and then not be able to weather a storm if one comes along. It’s not a fun topic, but it’s an important one. As CNET says:
“You’ll want to have a financial cushion that can cover several months of living expenses, including mortgage payments, in case of unforeseen circumstances, such as job loss or medical emergencies.”
4. How long do you plan to live there?
It was mentioned above, but buying a home comes with some upfront expenses. And while you’ll get that money back (and more) as you gain equity, that process takes some time. If you plan to move again soon, you may not recoup your full investment.
So, how long should you stay put in an ideal world? Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), explains:
“Five years is a good, comfortable mark. If the price of your home appreciates considerably, then even three years would be fine.”
So, think about your future. If you’re going to live there for a while, it may make sense to go for it. But, if you’re looking to sell and move within a year or two because you’re planning to transfer to a new city with that promotion you’ve been working so hard for, or you anticipate you’ll need to move to take care of family, those are things to factor in.
5. Do you have a team of real estate professionals in place?
If you do, great. But if you don’t, finding a trusted local agent and a lender is a good first step. Having the right team can make figuring out everything else easier. The pros can talk you through your options and help you decide if you’re ready to make your move, or if you have a few more things to get in order first.
Bottom Line
If you want to have a conversation about the most important things you need to consider when buying a home, let’s connect.


